A financial long term Template is a structured way to turn broad financial ambitions into a multi-year plan that can be measured, reviewed, and adjusted. Instead of looking only at the next month or financial year, it connects income, expenses, savings, investments, debt, major purchases, cash flow, and net worth across a longer horizon. The best format is not necessarily the most complicated one. It is the format that makes assumptions visible, keeps calculations consistent, and helps the reader make better decisions.
Search intent around a long-range financial template usually falls into two groups. Individuals want a practical planning framework for savings, retirement, debt reduction, major purchases, and wealth accumulation. Businesses want a forecasting structure that connects revenue assumptions with operating costs, capital spending, funding, profitability, liquidity, and strategic objectives. A useful template can support either purpose, but the inputs and level of detail should be adapted to the situation.
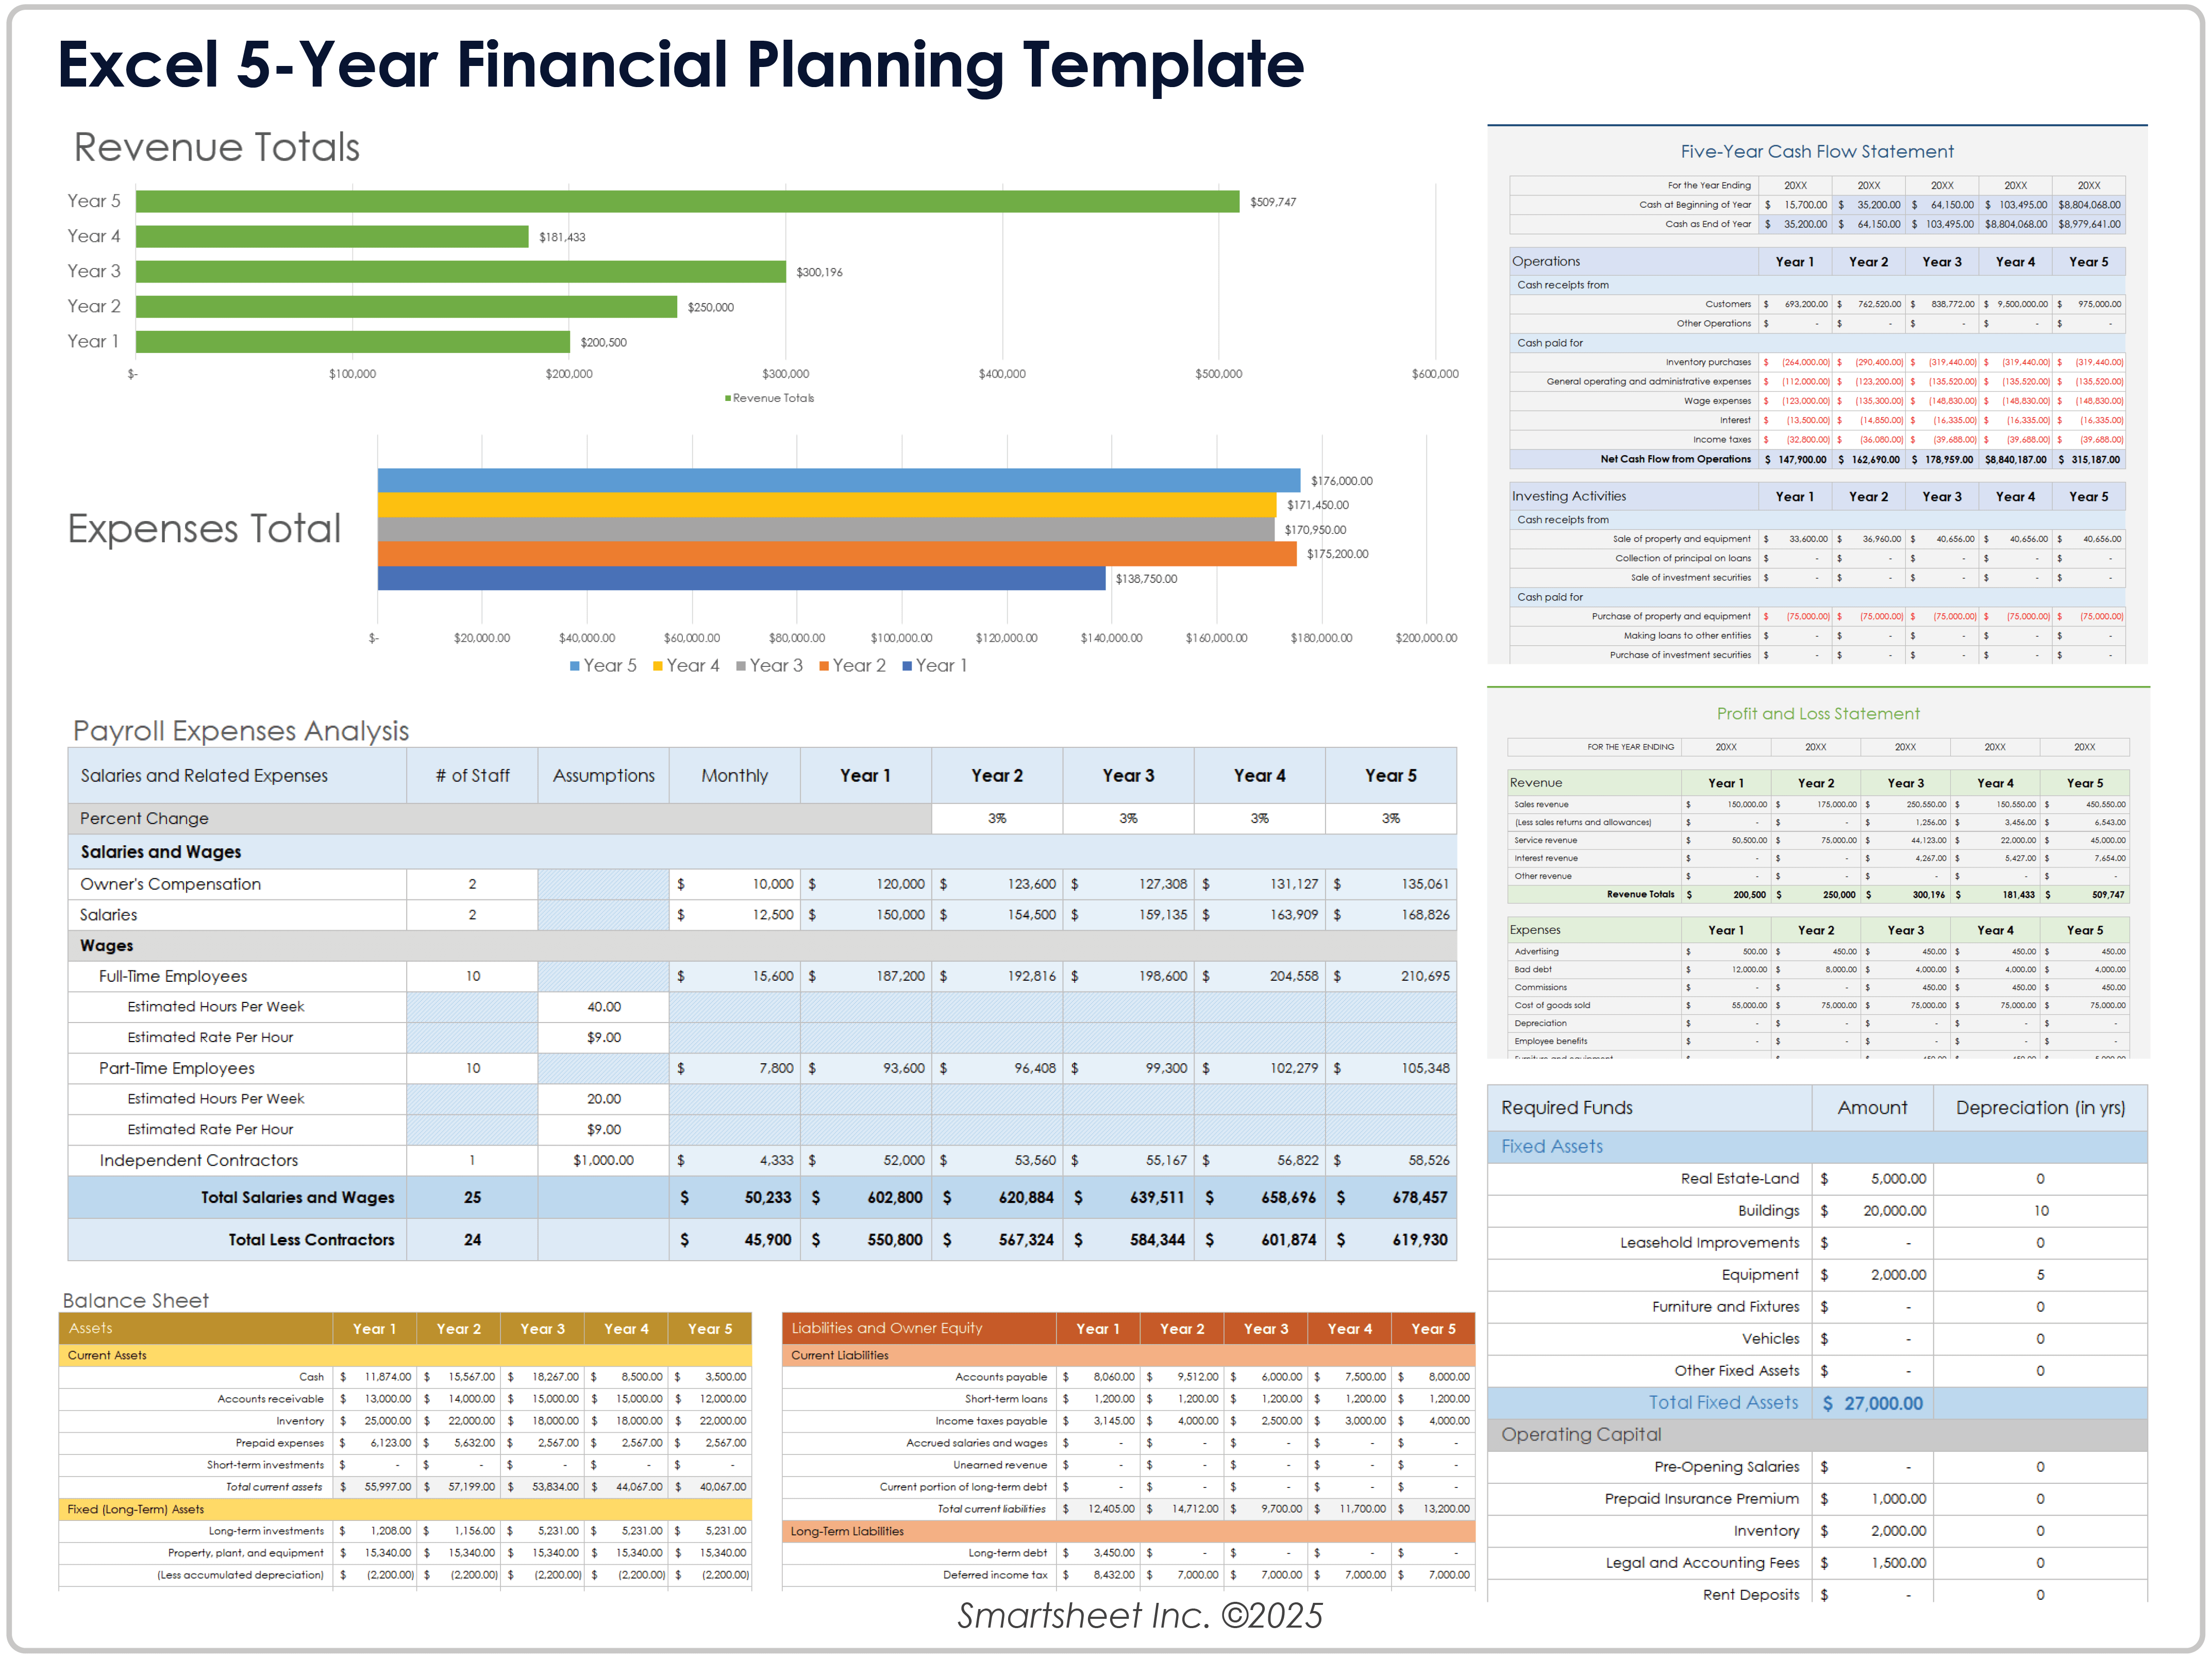
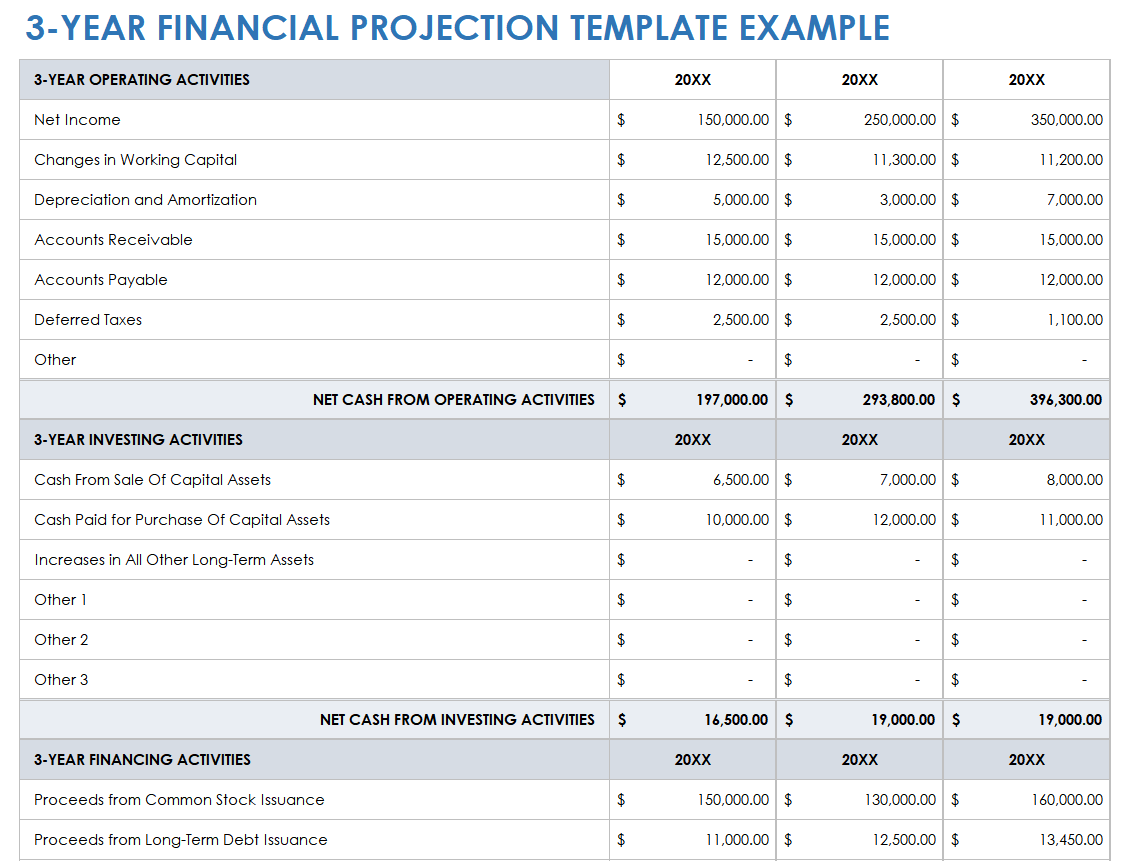
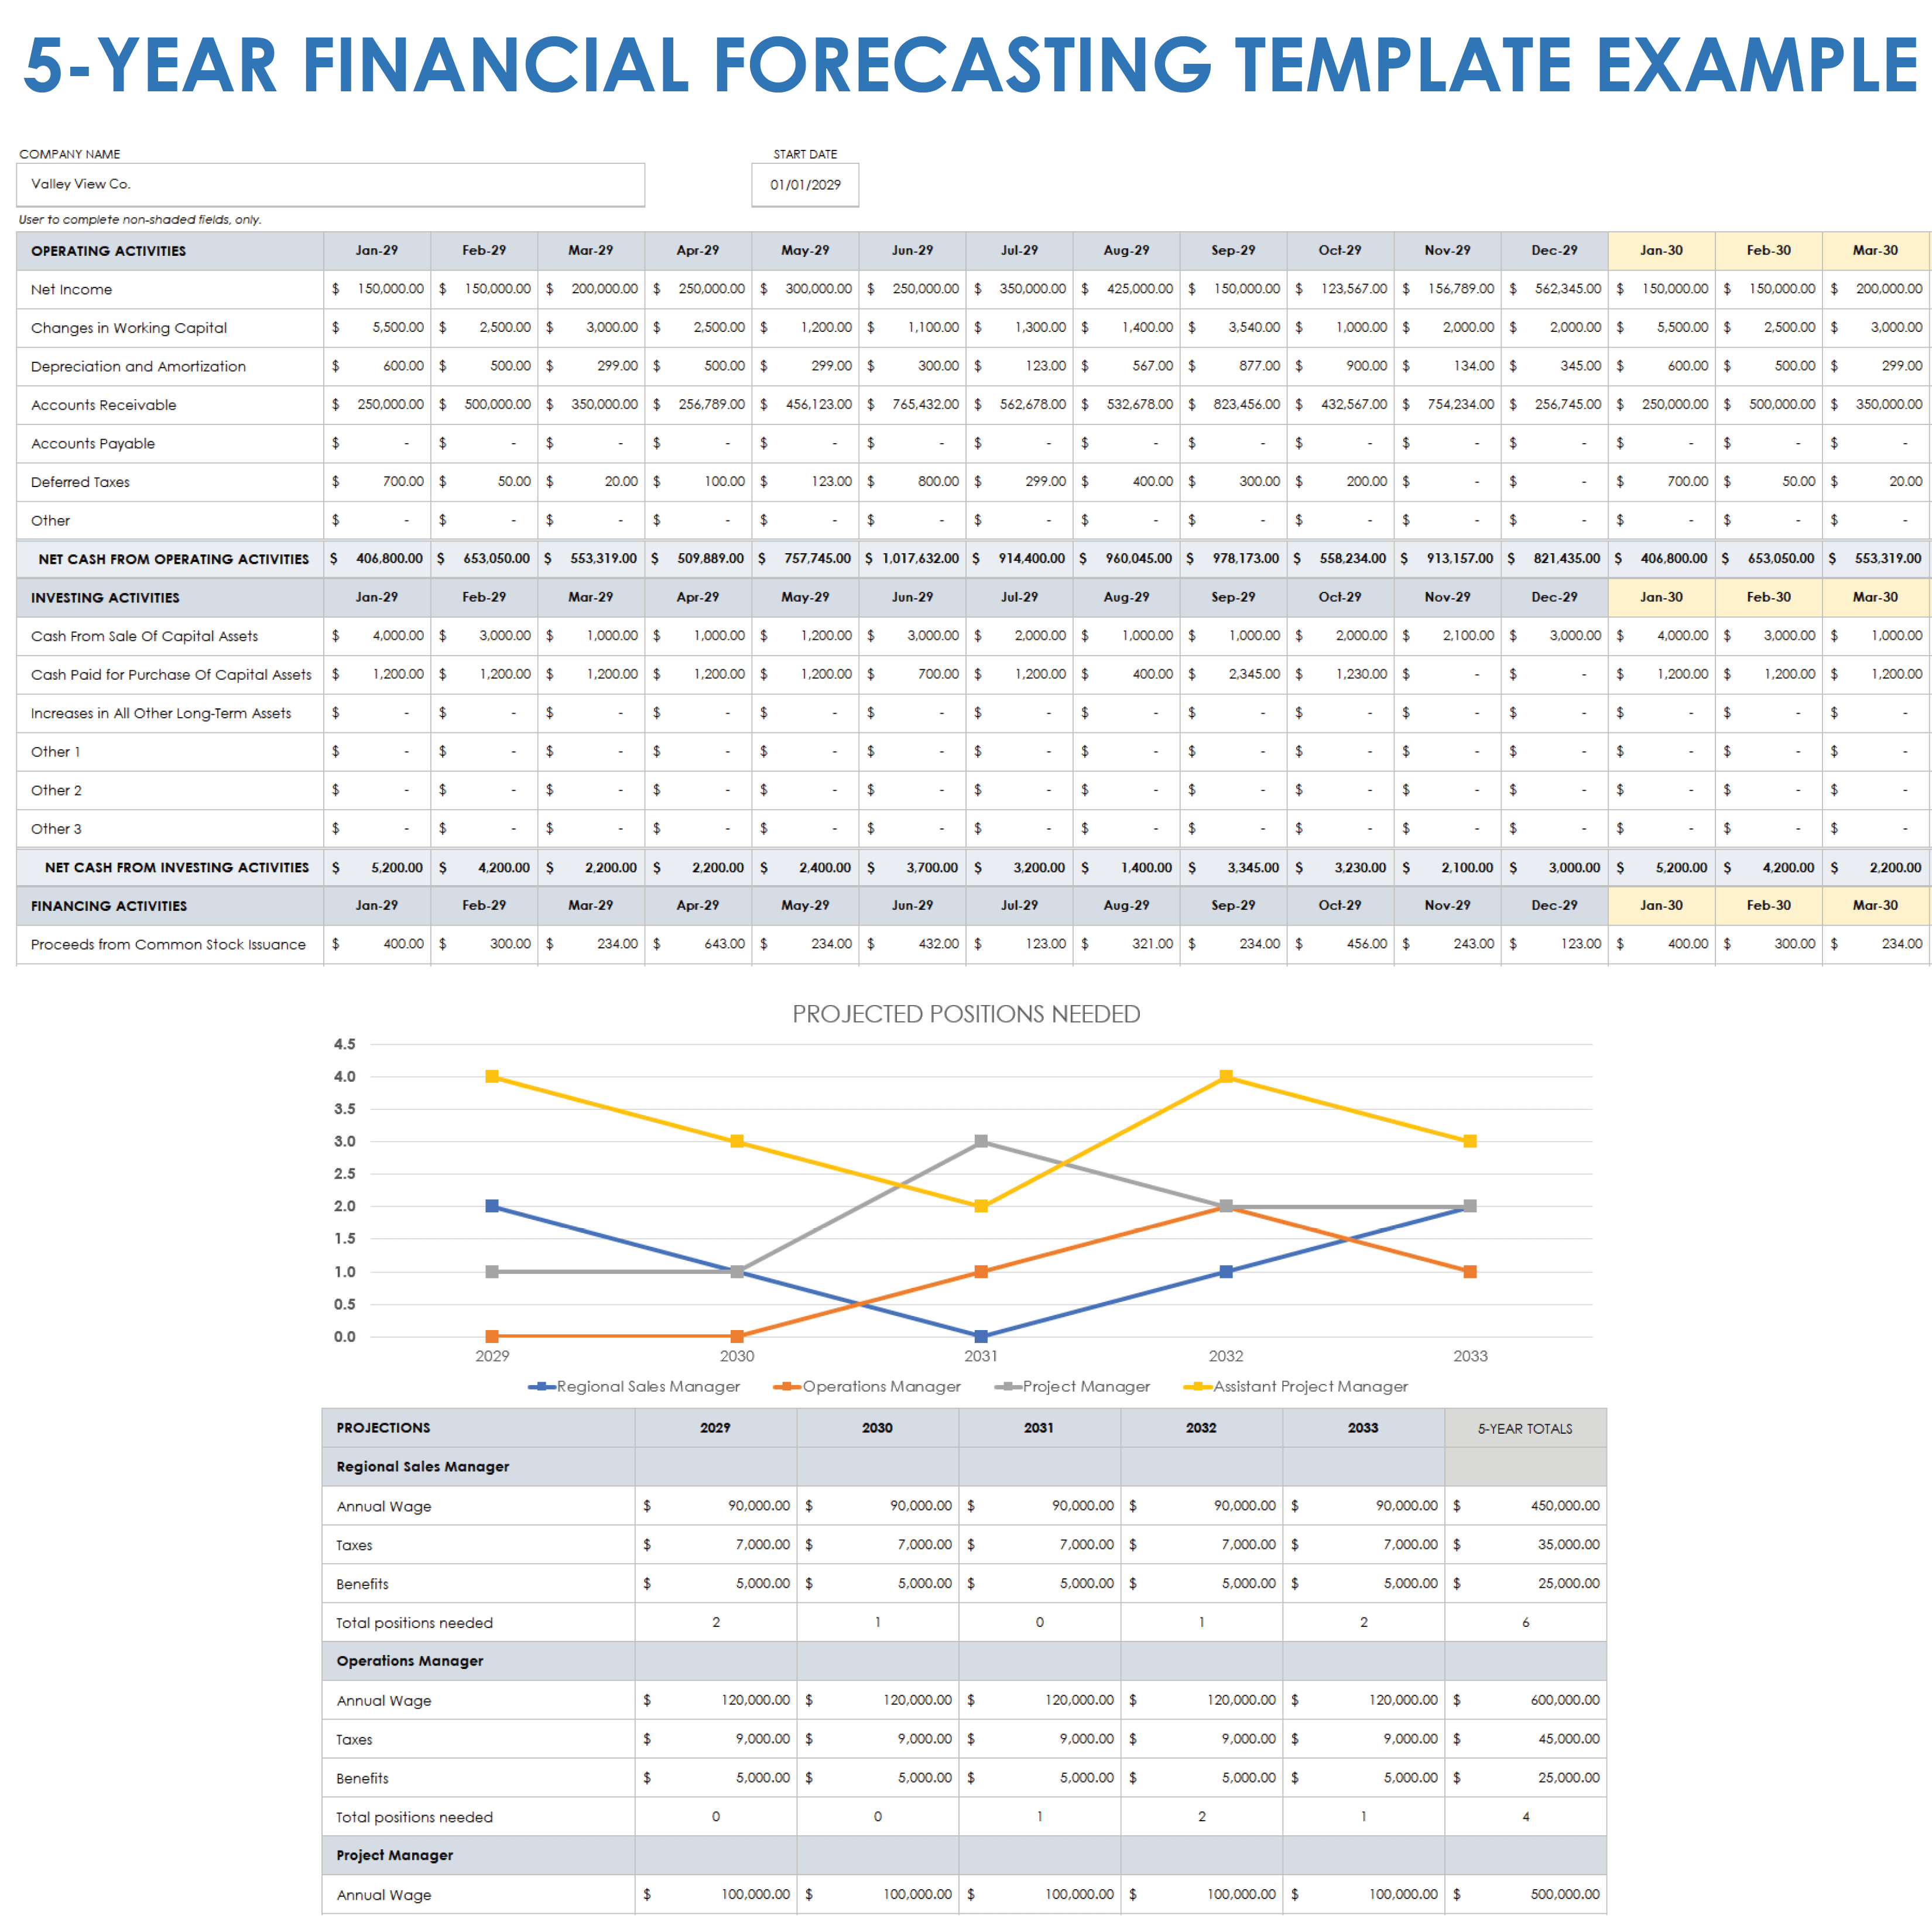
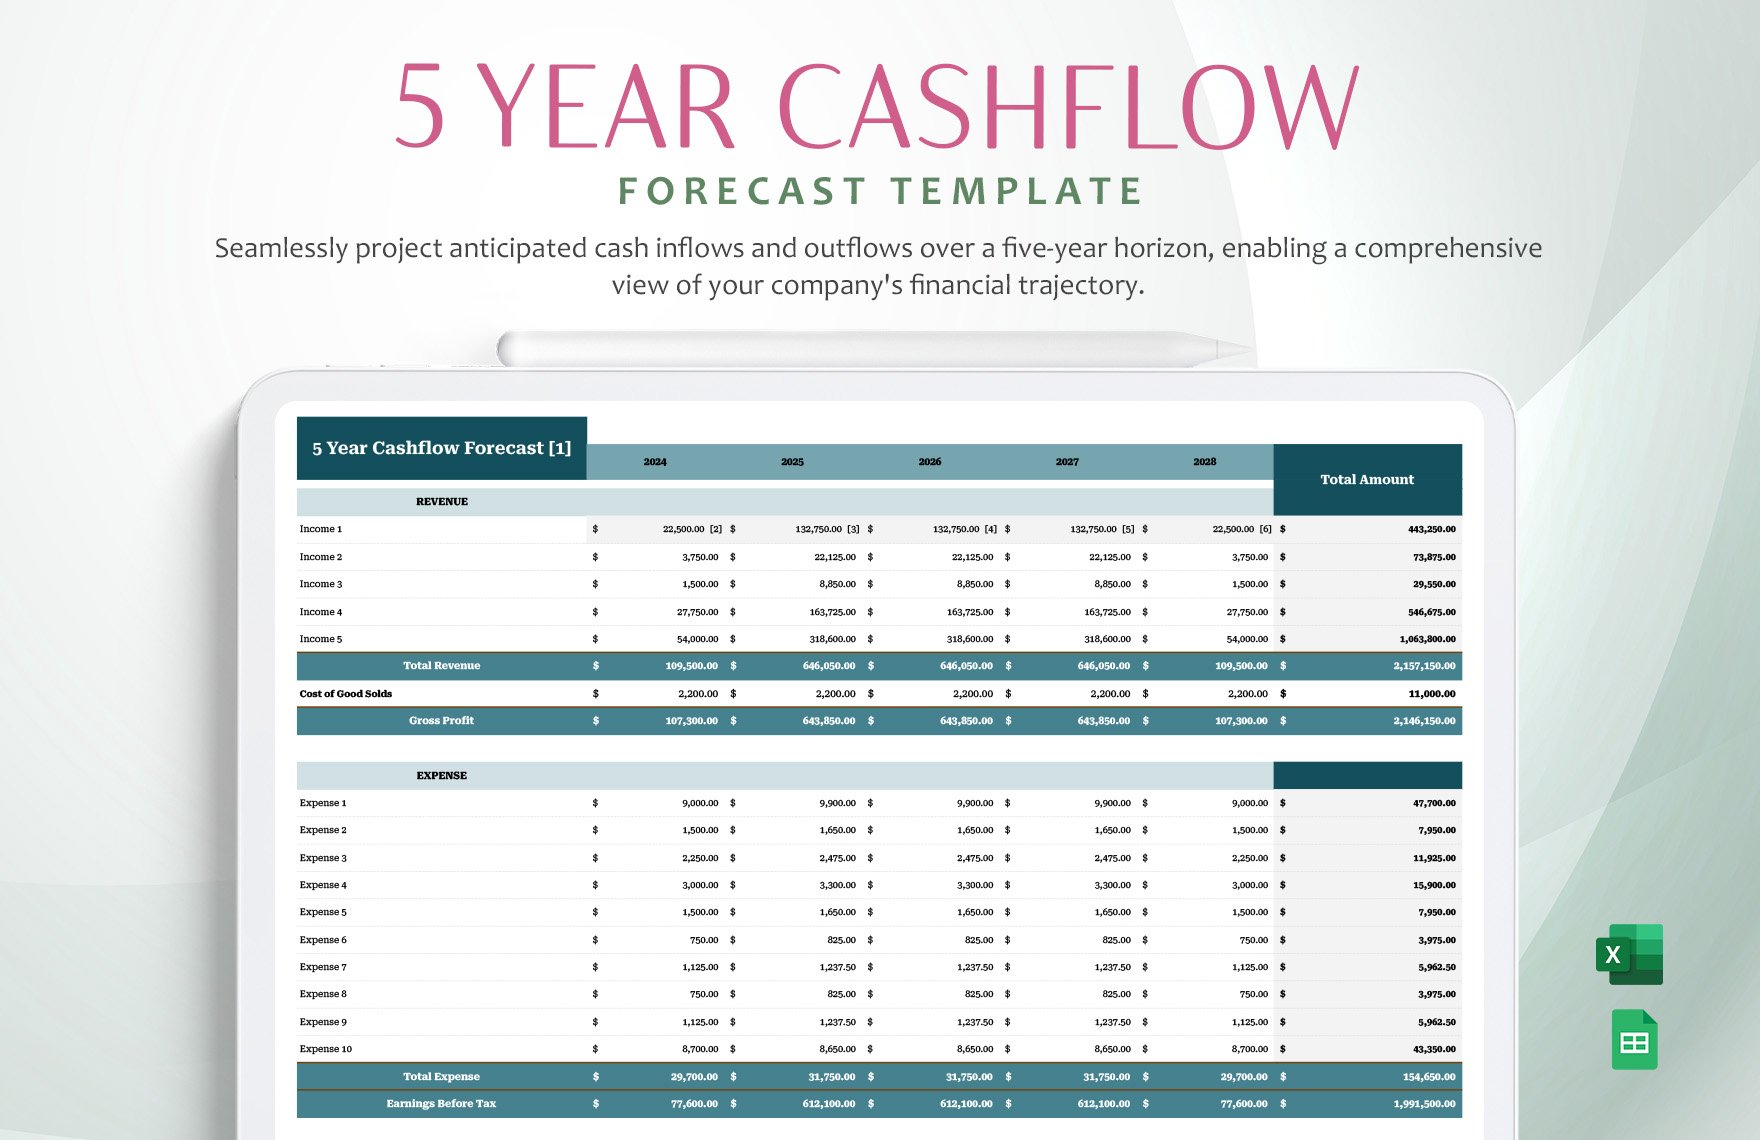
Several established financial planning formats illustrate the same underlying principle: future financial outcomes are modeled from assumptions rather than treated as certain facts. A multi-year model may contain annual revenue and expense projections, cash-flow estimates, balance-sheet positions, savings targets, investment contributions, or scenario comparisons. The purpose is to make relationships visible so that a change in one assumption can be evaluated before it becomes a real financial problem.
This guide explains what a strong long-range financial template should contain, how to structure it in a spreadsheet or document, how to build realistic assumptions, how to compare scenarios, and how to review the plan over time. It also explains how phrases such as financial long term template excel, financial long term template free download, and financial long term template google sheets relate to different ways of organizing the same planning process.
What a financial long term Template is designed to do
At its core, a long-term financial template is a planning model rather than a prediction machine. It provides a consistent structure for entering current financial information, setting future assumptions, and calculating how those assumptions may affect financial outcomes. A well-built model separates inputs from formulas, so the user can change a growth rate, savings contribution, expense assumption, or debt payment without rebuilding the entire plan.
The time horizon depends on the decision being considered. A business may use three, five, or ten years for strategic planning, while a household may need a much longer horizon for retirement or education planning. The farther the horizon extends, the more important it becomes to distinguish between information that is relatively observable and assumptions that are inherently uncertain. A useful plan therefore shows the direction of the finances rather than pretending that every future figure can be known precisely.
The template also creates a common language for financial decisions. Instead of saying that a company wants to grow rapidly or that a household wants to build wealth, the model can translate those objectives into measurable targets such as annual revenue, operating margin, savings contributions, debt balances, investment balances, cash reserves, or projected net worth. This turns vague ambitions into a framework that can be reviewed and challenged.
Why long-term financial planning needs a structured template
Long-range planning becomes difficult when financial information is scattered across unrelated notes, worksheets, bank records, budgets, and projections. A template creates a central structure in which the major components can be connected. For example, an increase in sales should influence revenue, cash receipts, operating costs, taxes, working capital, and potentially funding requirements. A personal savings increase may affect cash reserves, investment balances, and the timing of a major purchase.
Another advantage is comparability. If the same categories are tracked every year, the user can compare the original plan with updated expectations and actual results. This is particularly valuable when circumstances change. A business may discover that customer acquisition costs are higher than expected, while a household may find that housing or education costs have changed. The model can be revised without losing the original planning assumptions.
A structured model also helps identify trade-offs. More spending in one area may reduce savings, increase borrowing, or delay an investment target. Faster expansion may increase revenue while also requiring additional employees, equipment, inventory, or working capital. Long-term planning is therefore not simply about producing a larger future number. It is about showing how different choices interact.
Core components of a long term financial plan
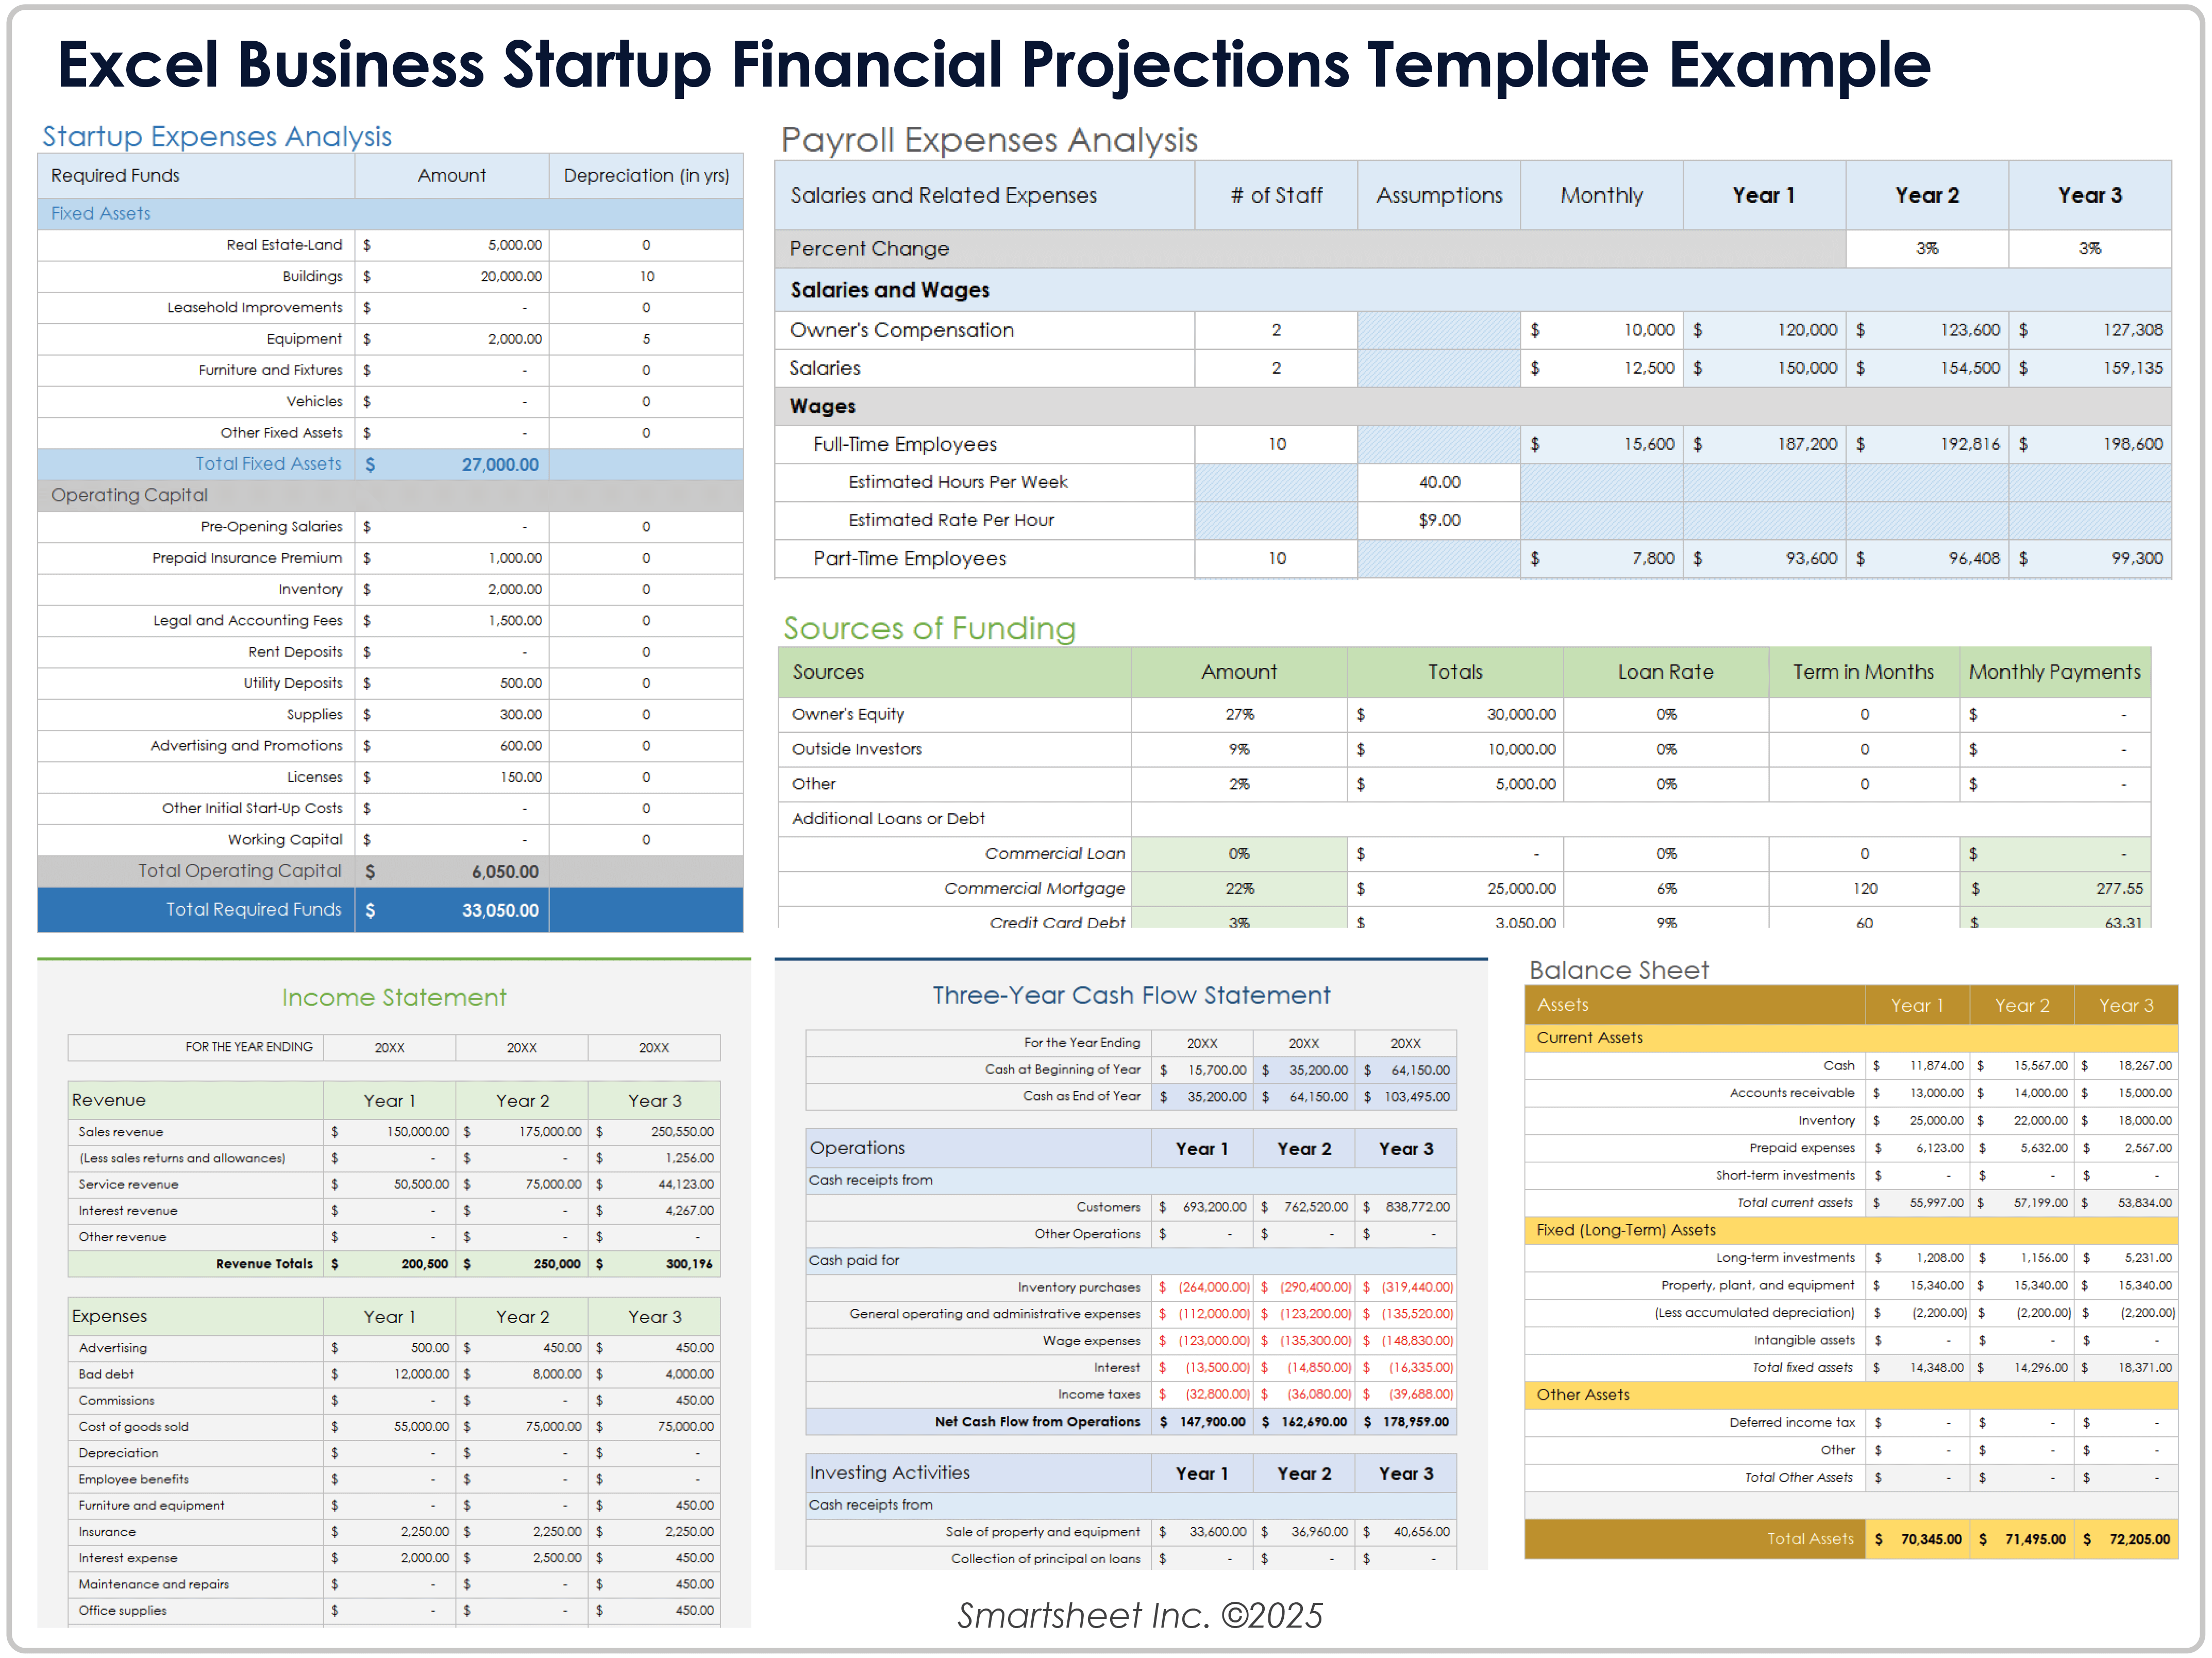
A practical long term financial planning template should begin with a clearly defined starting position. For a business, this may include current cash, receivables, inventory, fixed assets, liabilities, existing debt, equity, revenue, and operating expenses. For an individual, it may include income, recurring expenses, savings, investments, property, loans, and other material assets or obligations. The opening position matters because every future projection builds from it.
The next layer is a set of assumptions. These can include expected income growth, pricing changes, inflation, hiring, operating costs, tax assumptions, investment contributions, debt repayment, capital purchases, and timing of major events. Assumptions should be easy to locate and clearly labeled. Separating assumptions from calculated results makes the model easier to audit and reduces the risk of accidentally overwriting formulas.
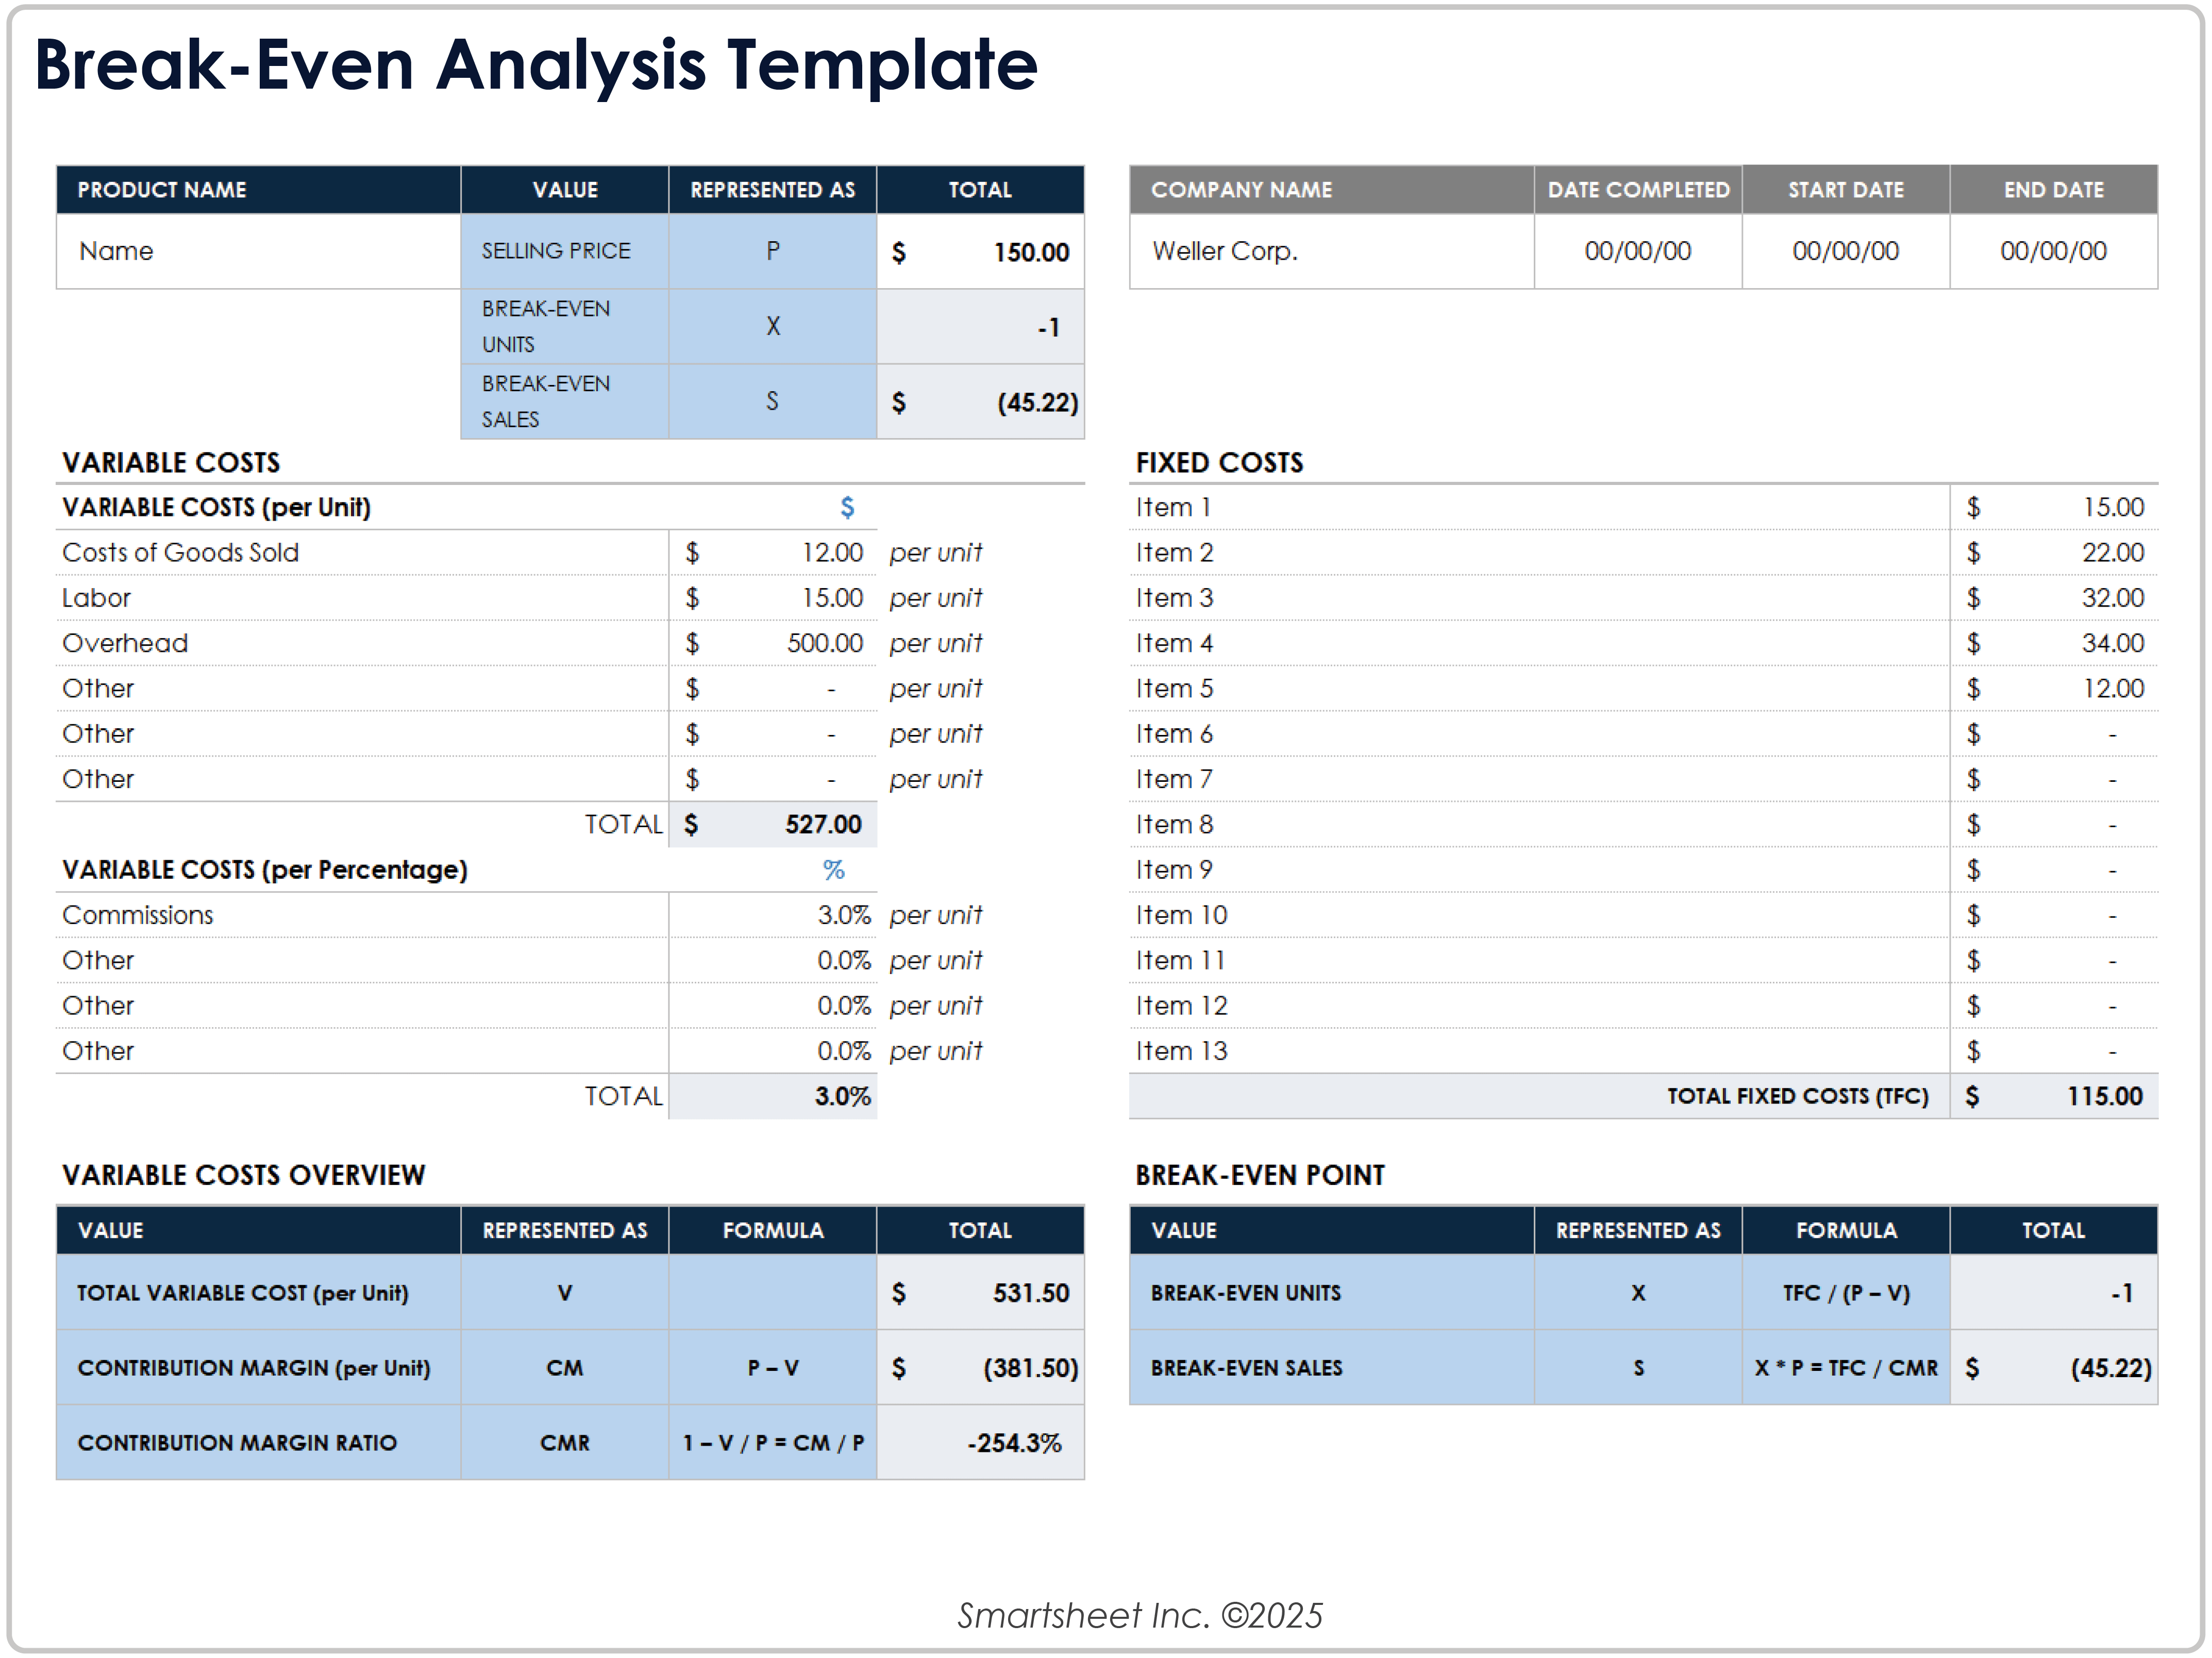
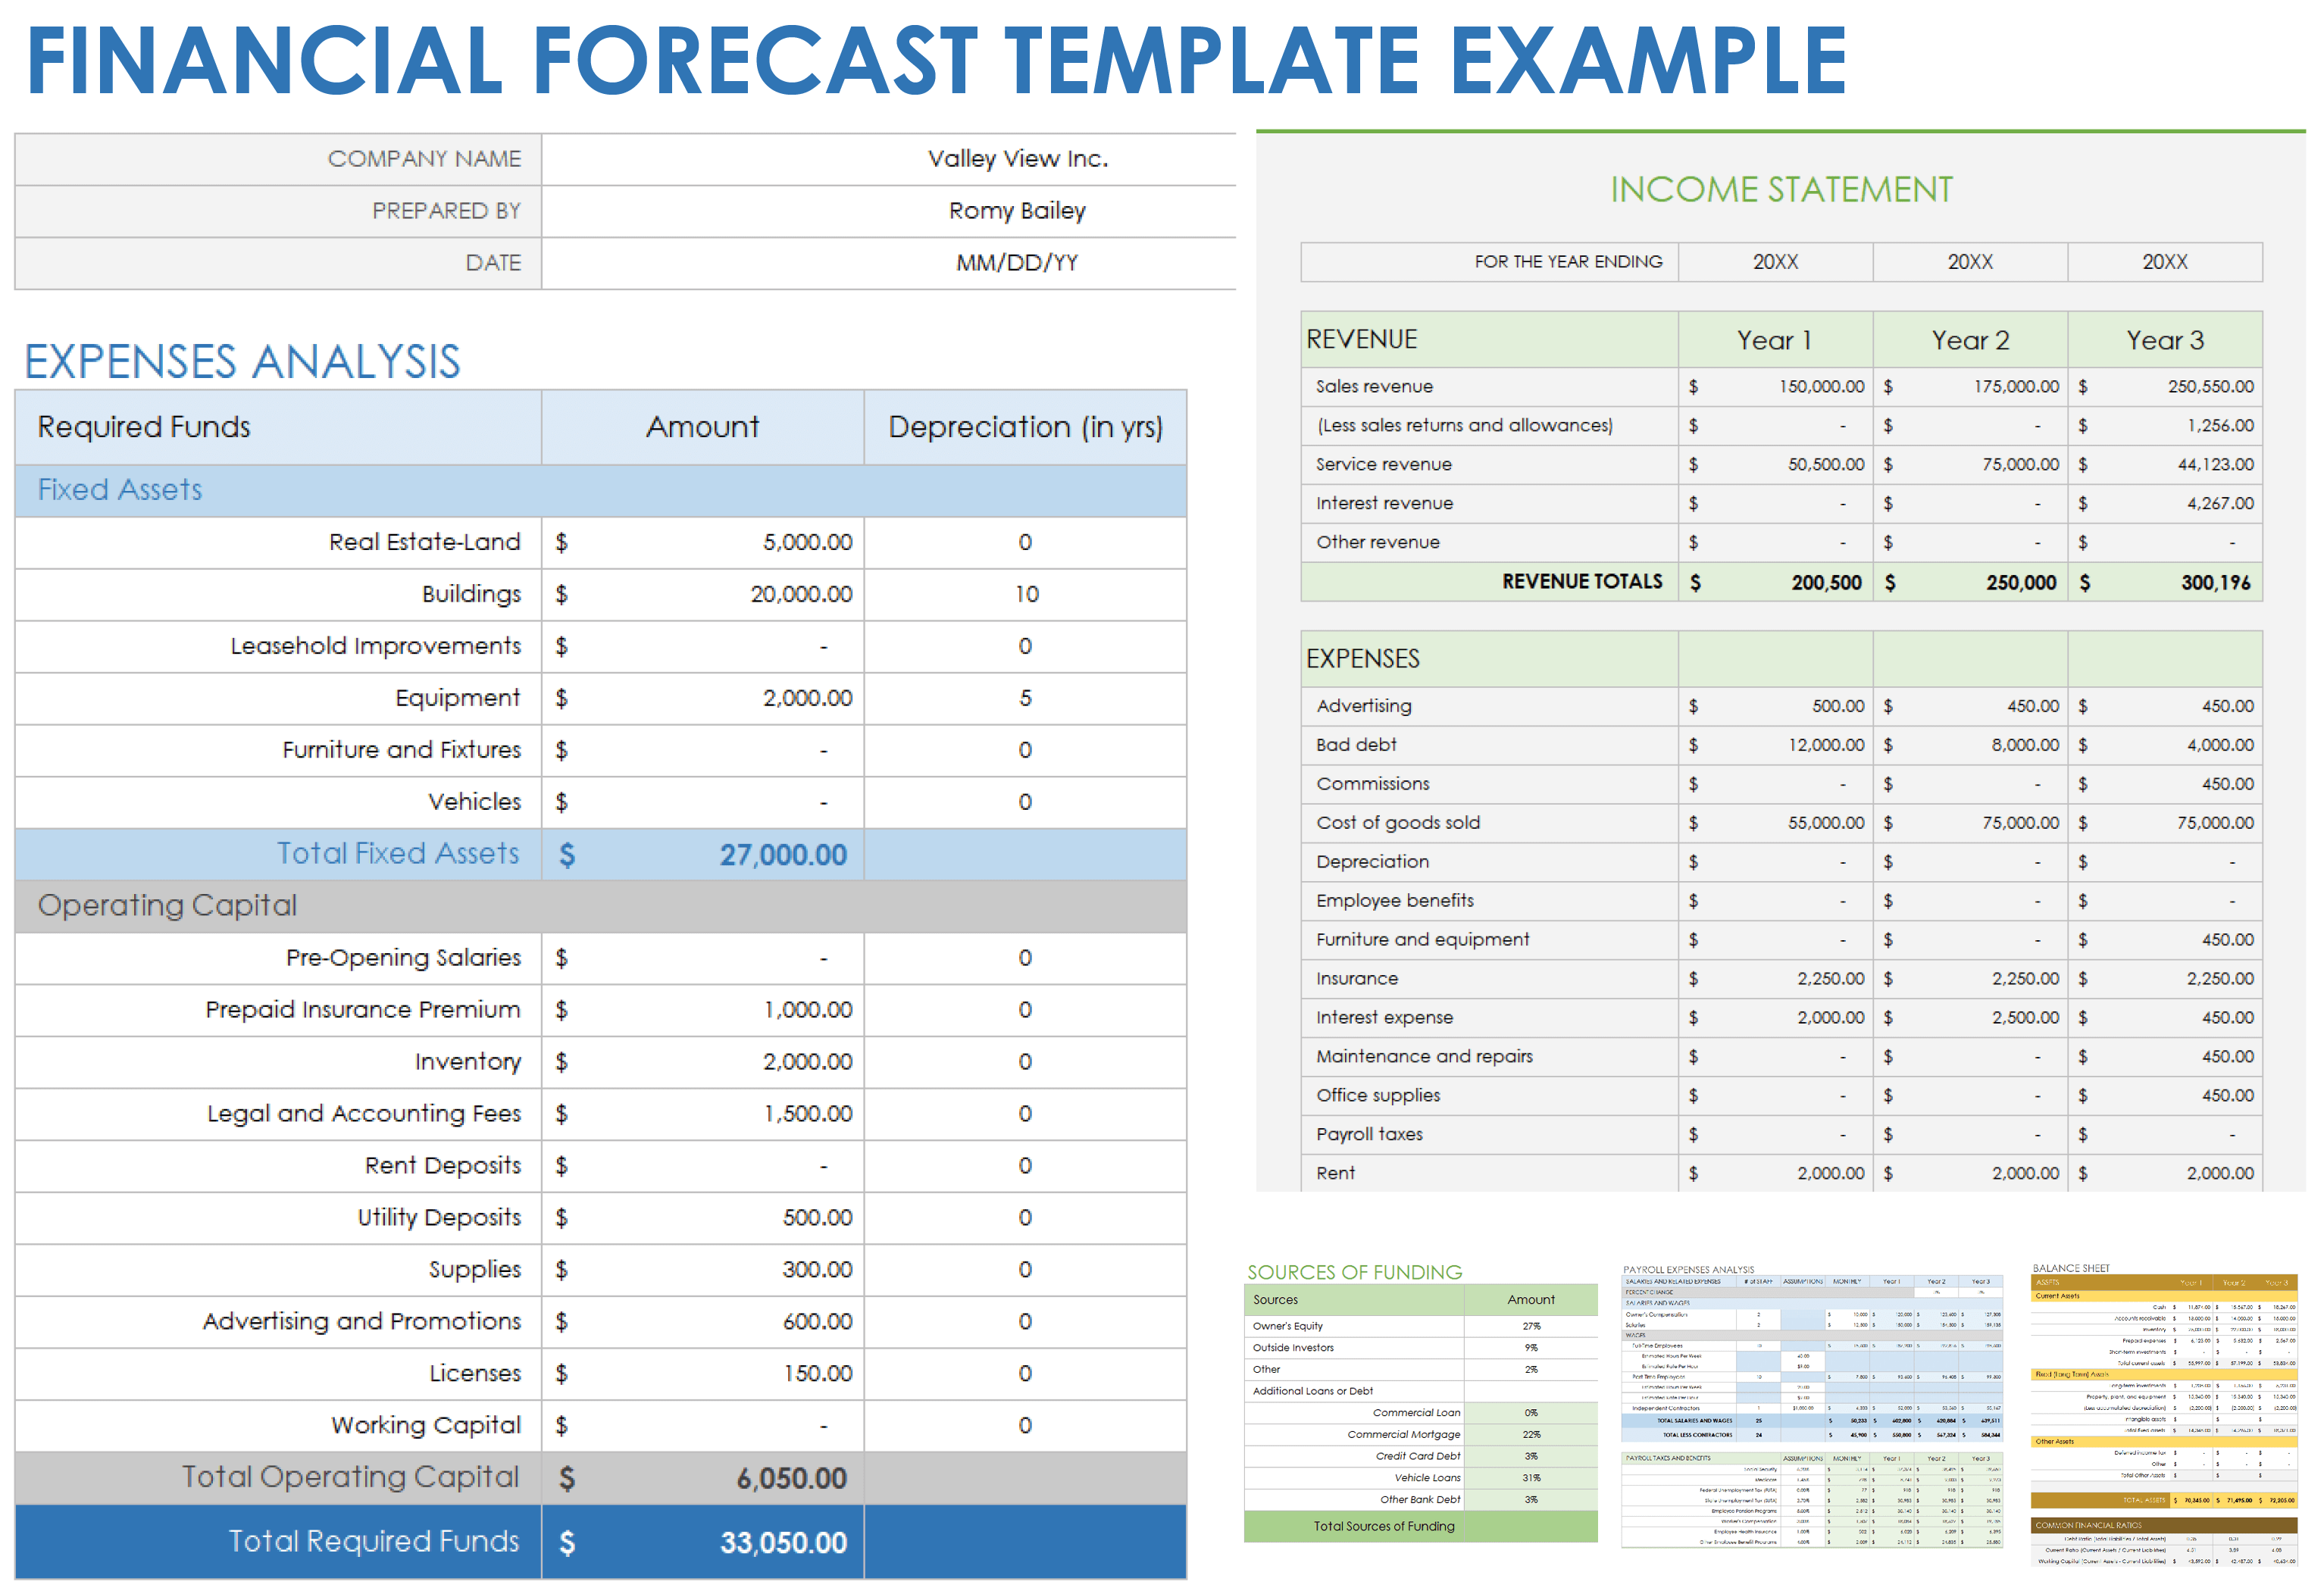
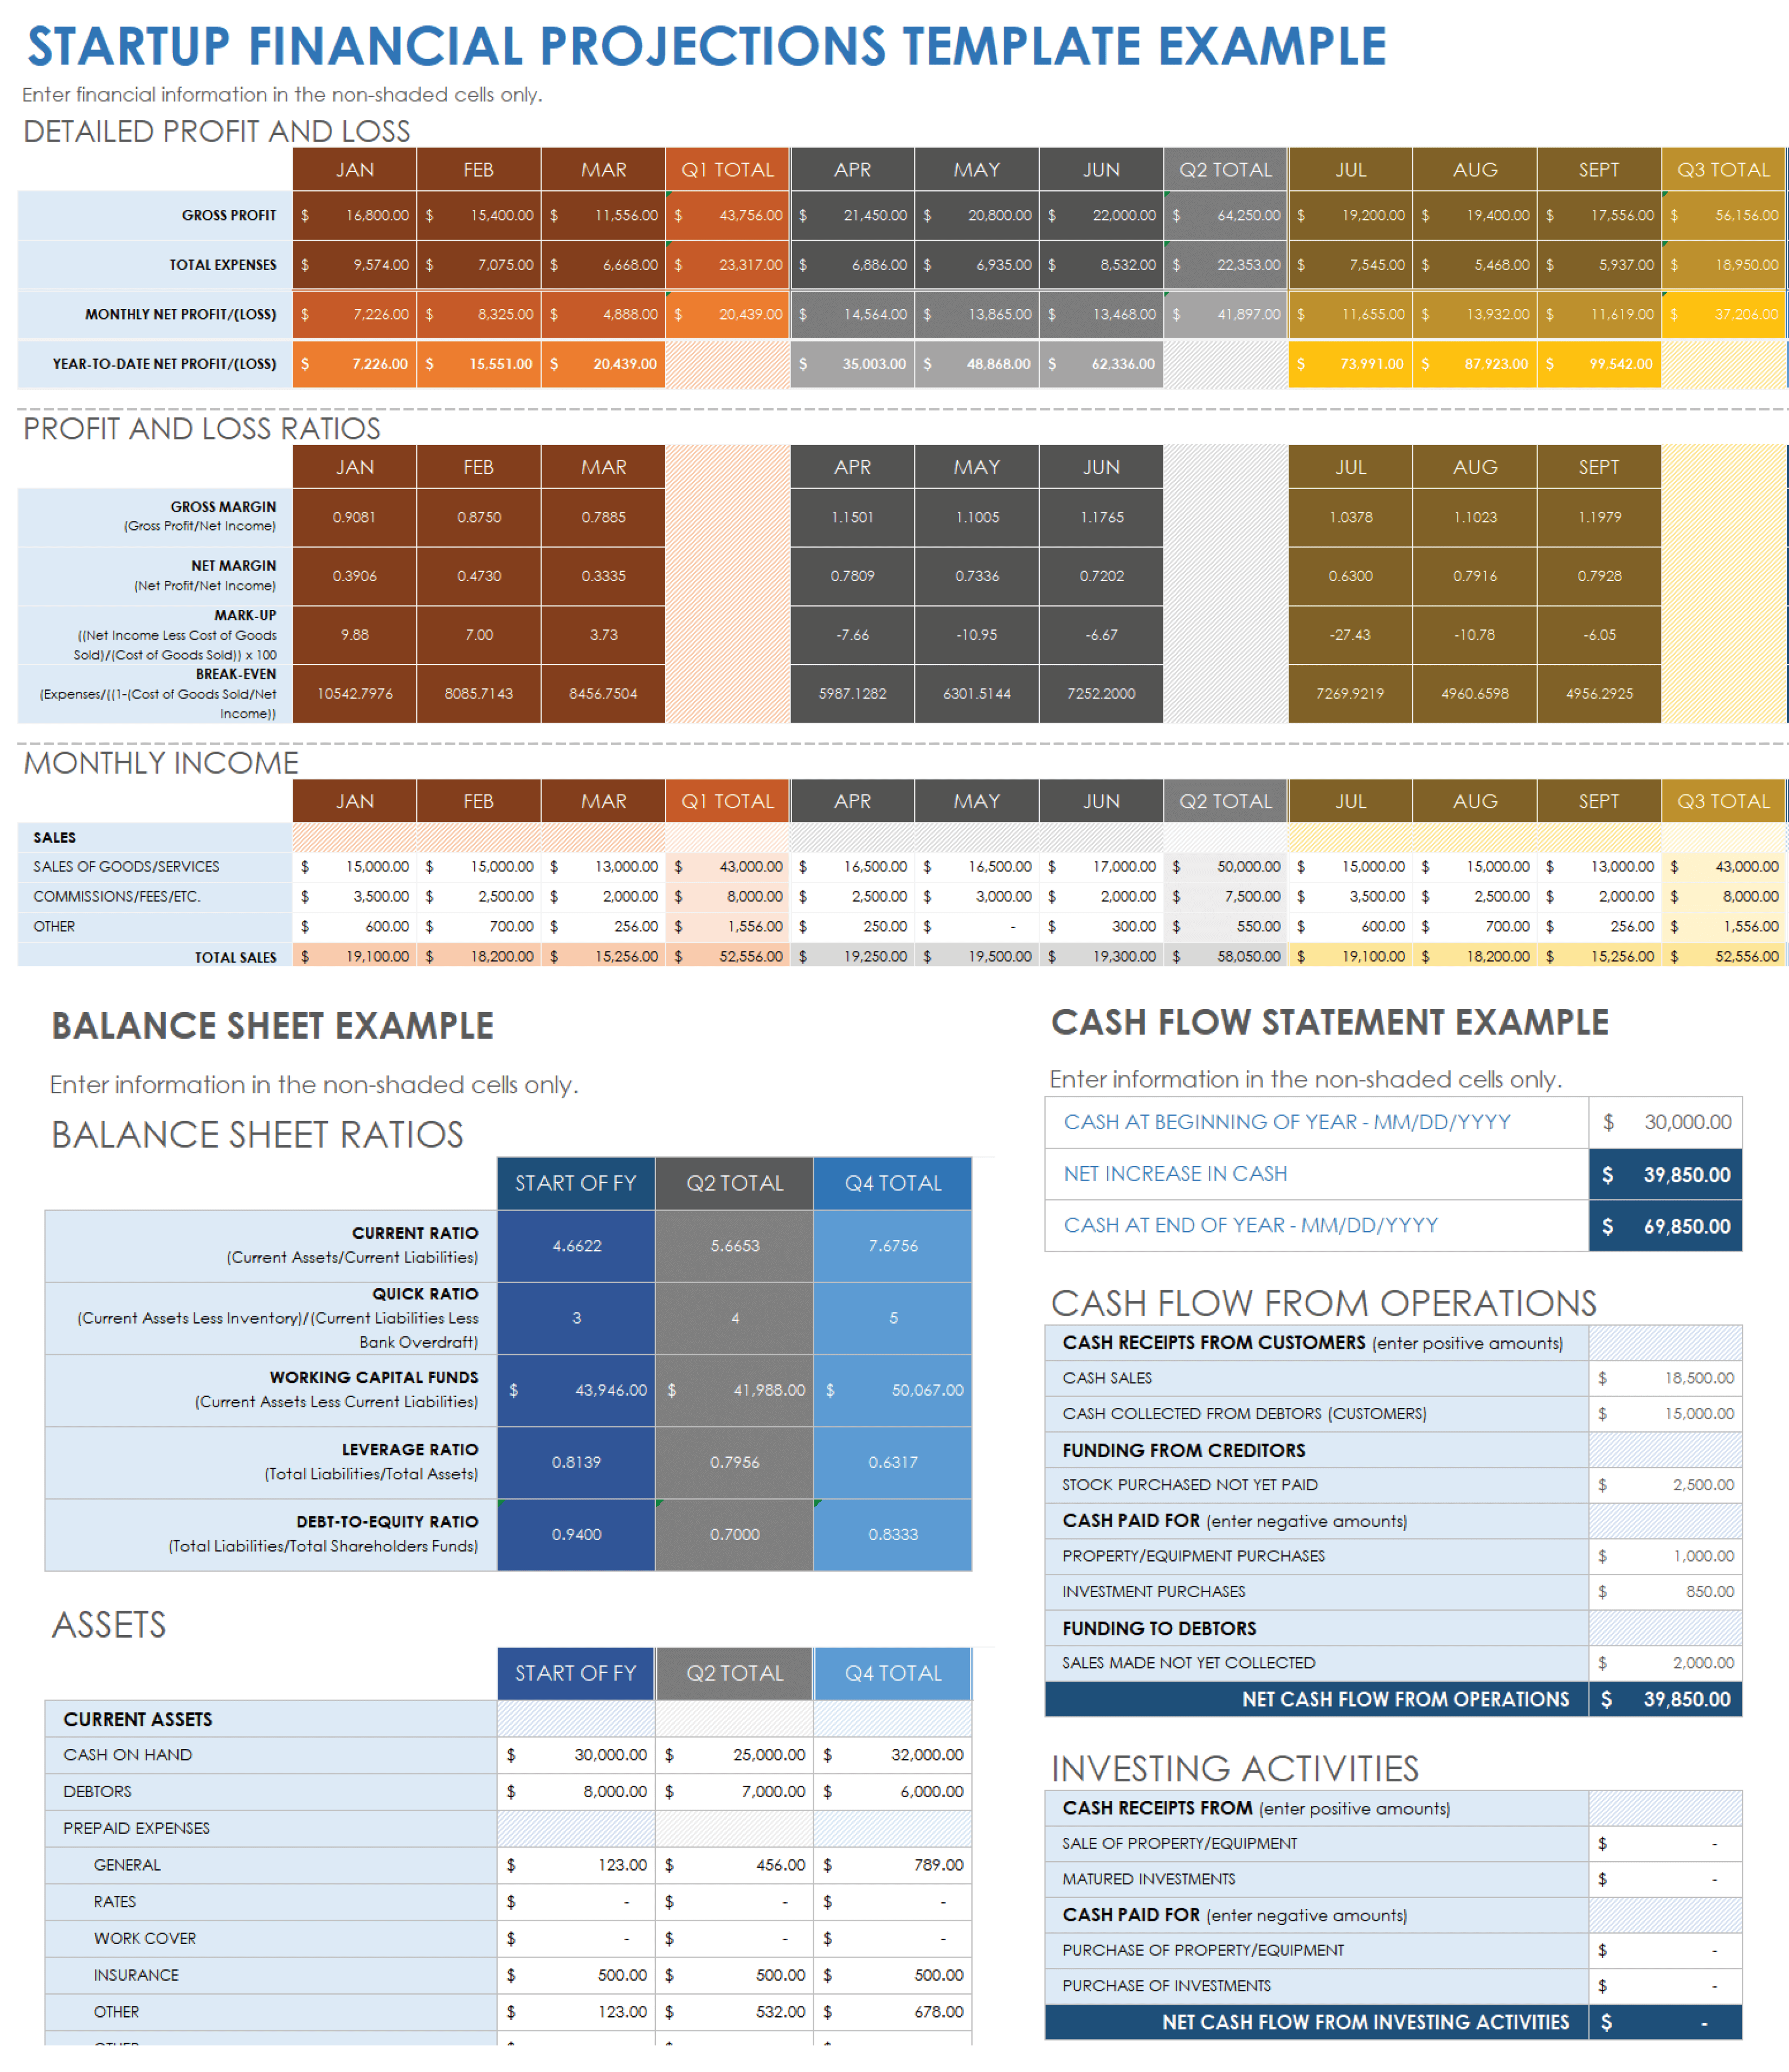
The final layer is the output. Useful outputs include annual income, total expenses, operating profit, net cash flow, ending cash, debt balance, savings, investment value, assets, liabilities, and net worth. For businesses, a more formal model may also include an income statement, balance sheet, cash-flow statement, break-even analysis, capital expenditure schedule, and funding plan. The right output depends on the decisions the model is intended to support.
- Starting position: Current financial balances and relevant historical information.
- Assumptions: Growth rates, inflation, costs, contributions, financing, and timing.
- Operating forecast: Expected income, revenue, expenses, and margins.
- Cash-flow forecast: Expected cash inflows, outflows, and ending liquidity.
- Balance-sheet view: Assets, liabilities, equity, savings, or net worth.
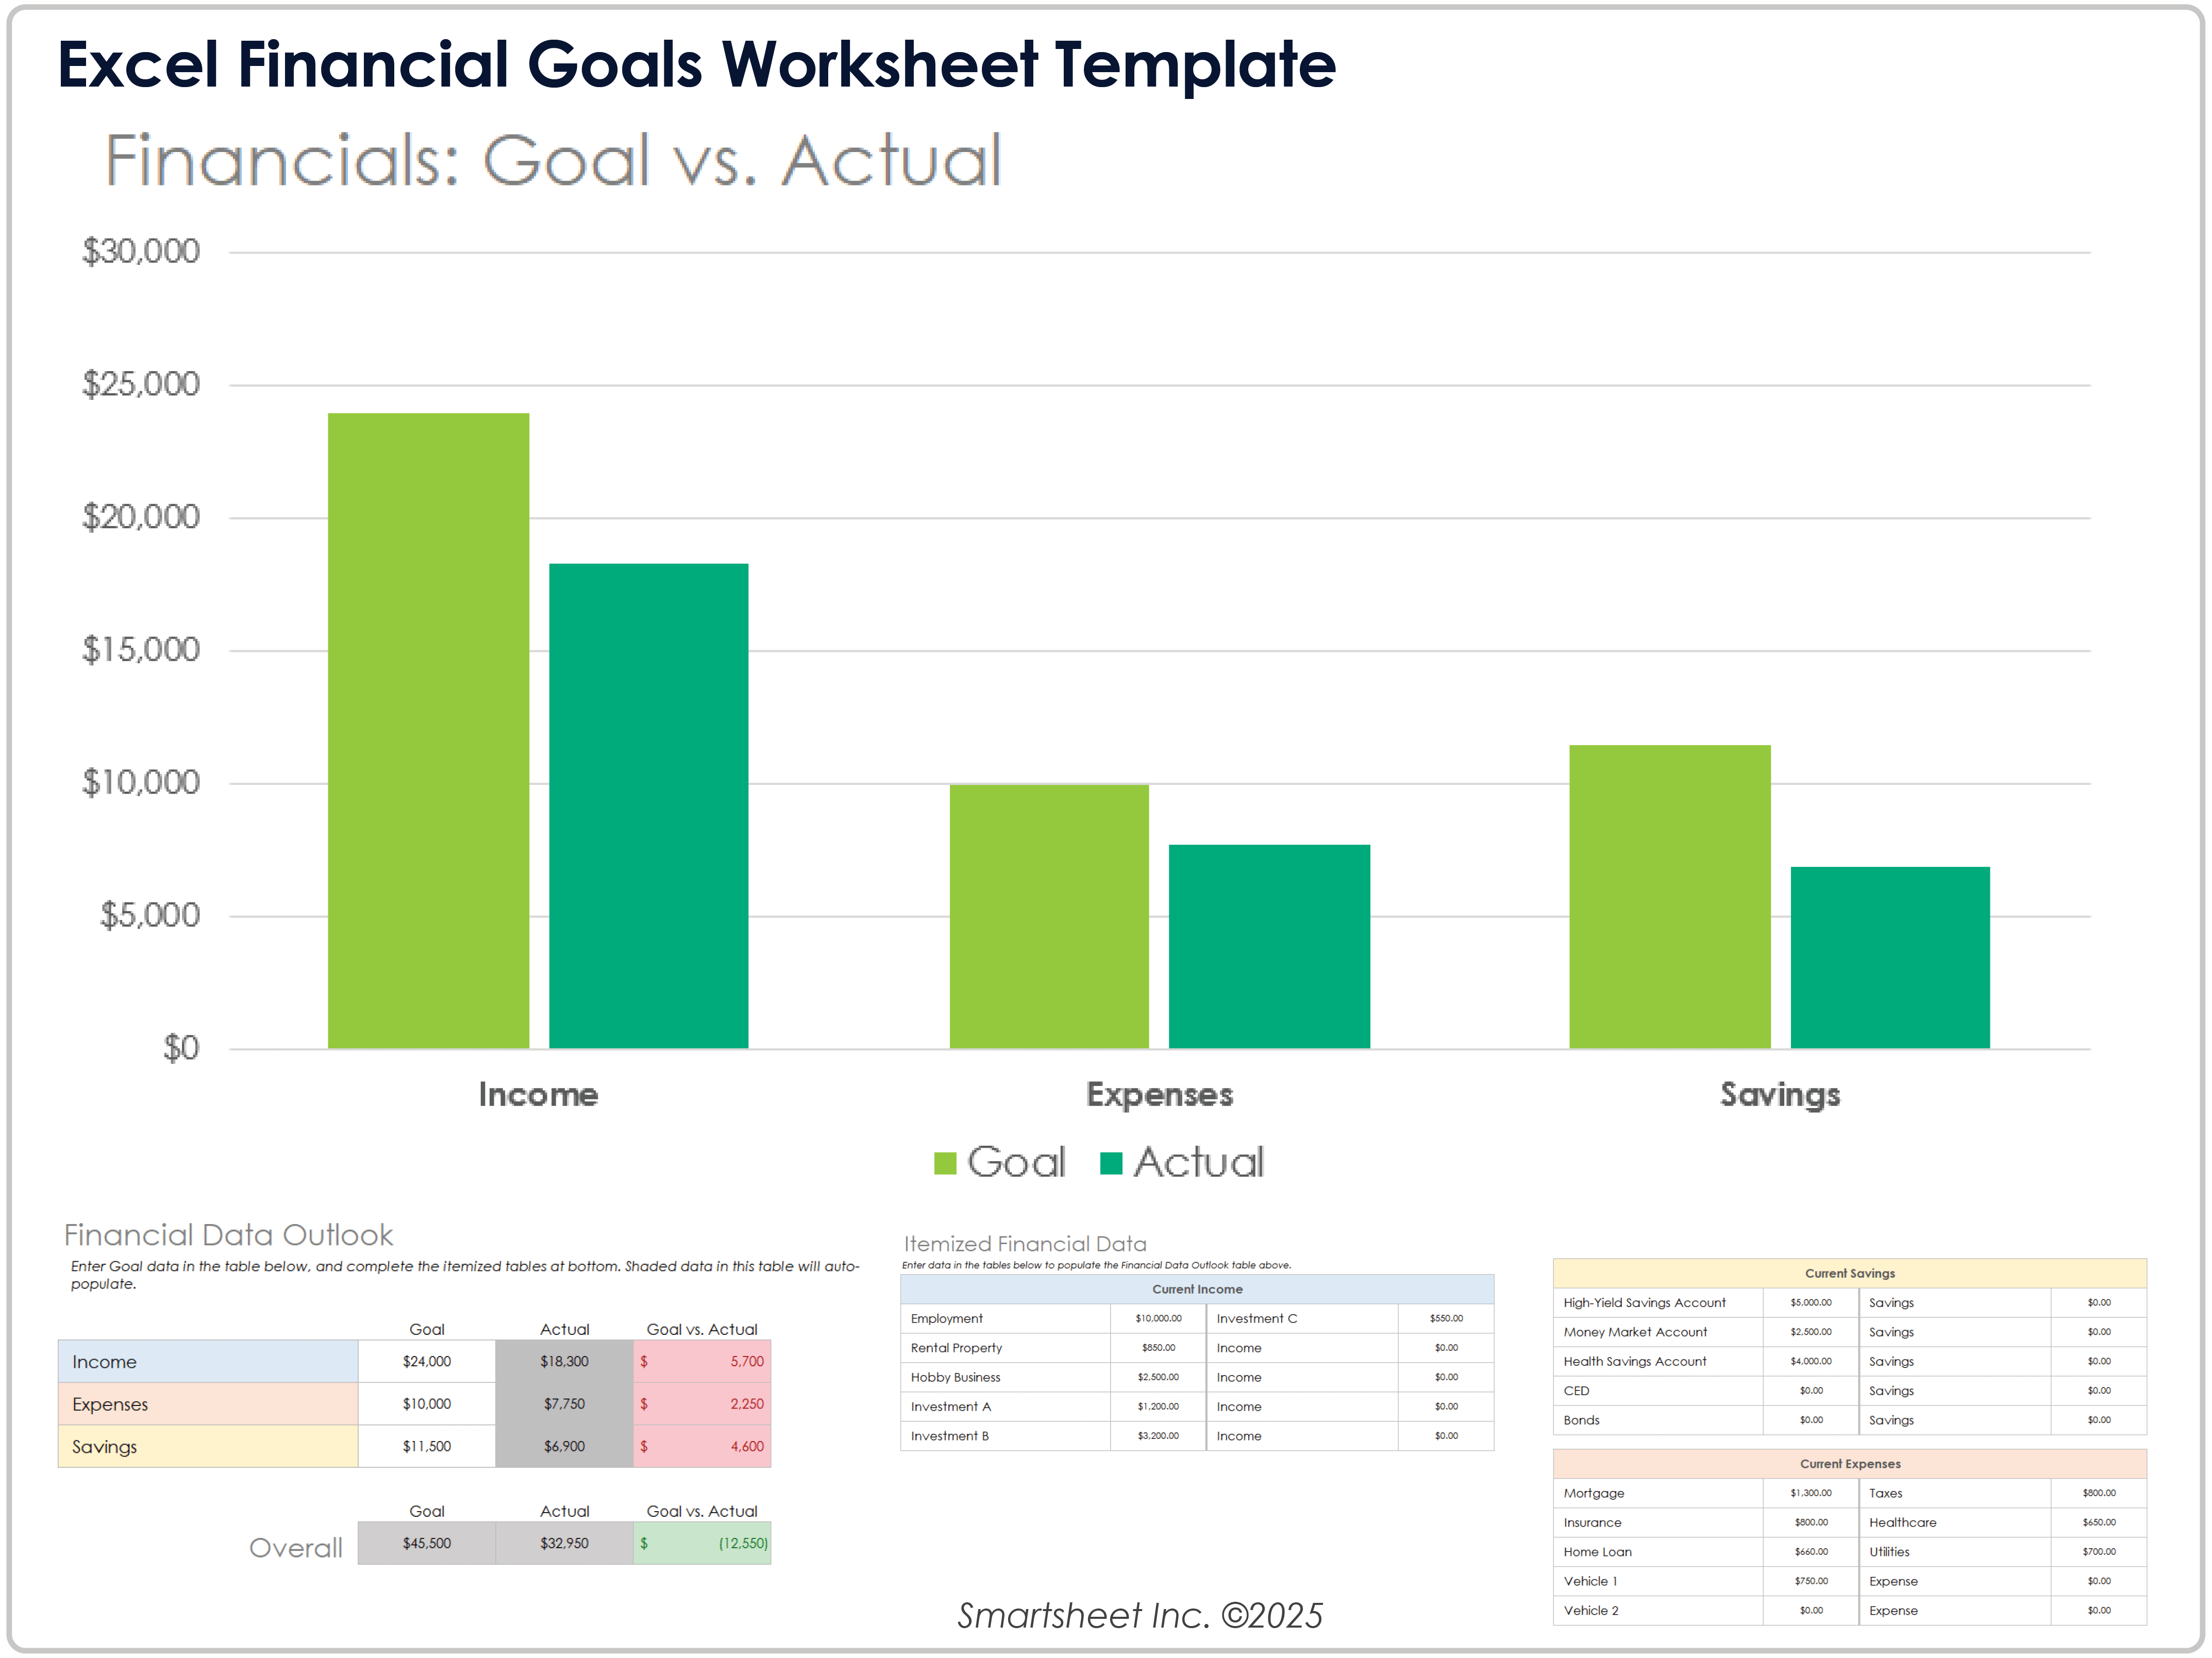
- Goals: Measurable financial targets and target dates.
- Scenarios: Base, stronger, weaker, or stress cases.
Choosing the right planning horizon
A three-year model can be useful when the objective is to understand near-to-medium-term operating decisions, while a five-year model is often more suitable for strategic business planning and major investment decisions. A ten-year horizon can be useful for major personal goals, retirement planning, property decisions, or long-lived investments. The important point is that the horizon should match the decision rather than being selected simply because a particular template contains a certain number of columns.
Long horizons require more caution because uncertainty compounds. A small difference in an annual growth assumption can create a substantial difference many years later. This is why a strong financial model should show assumptions clearly and support scenario analysis. Rather than asking whether one distant figure is correct, the user can ask how the outcome changes when several reasonable assumptions are tested.
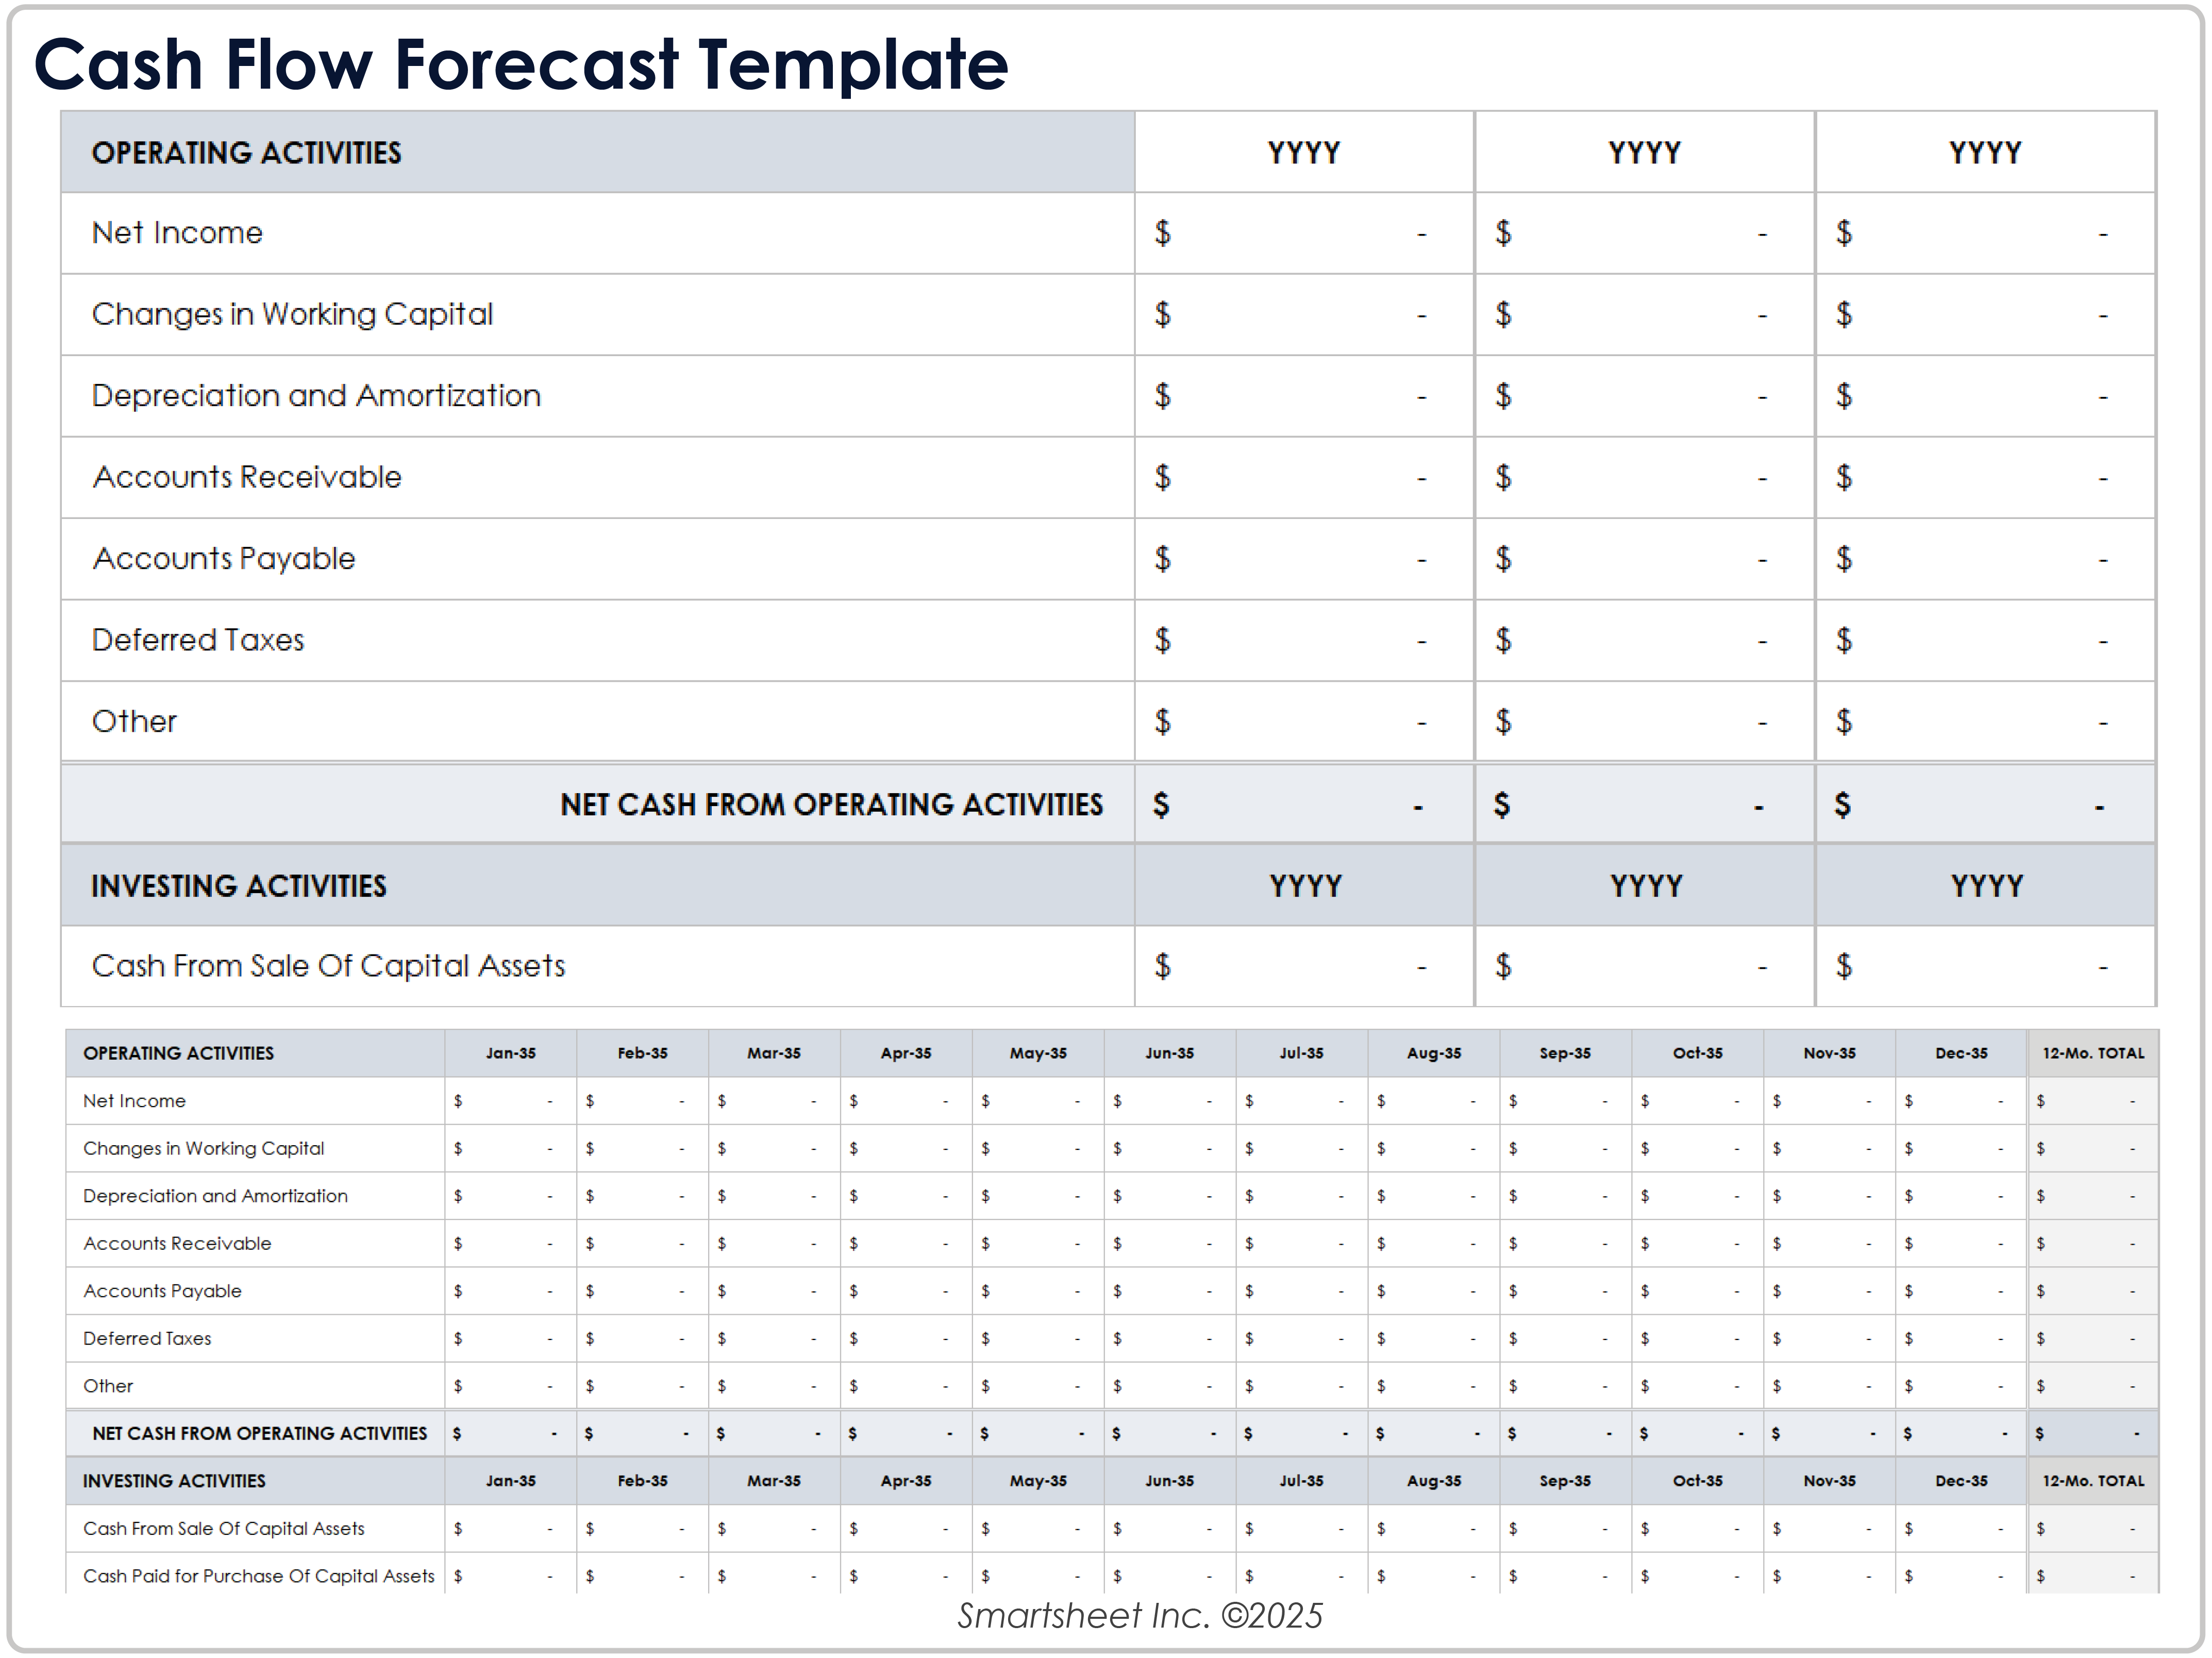
It is also useful to combine time scales. A long-range annual model can provide strategic direction, while the current year can be managed in greater detail with monthly or quarterly figures. This creates a bridge between long-term objectives and short-term execution. A five-year goal becomes more useful when the first year contains concrete targets that can be reviewed regularly.
Building revenue and income assumptions
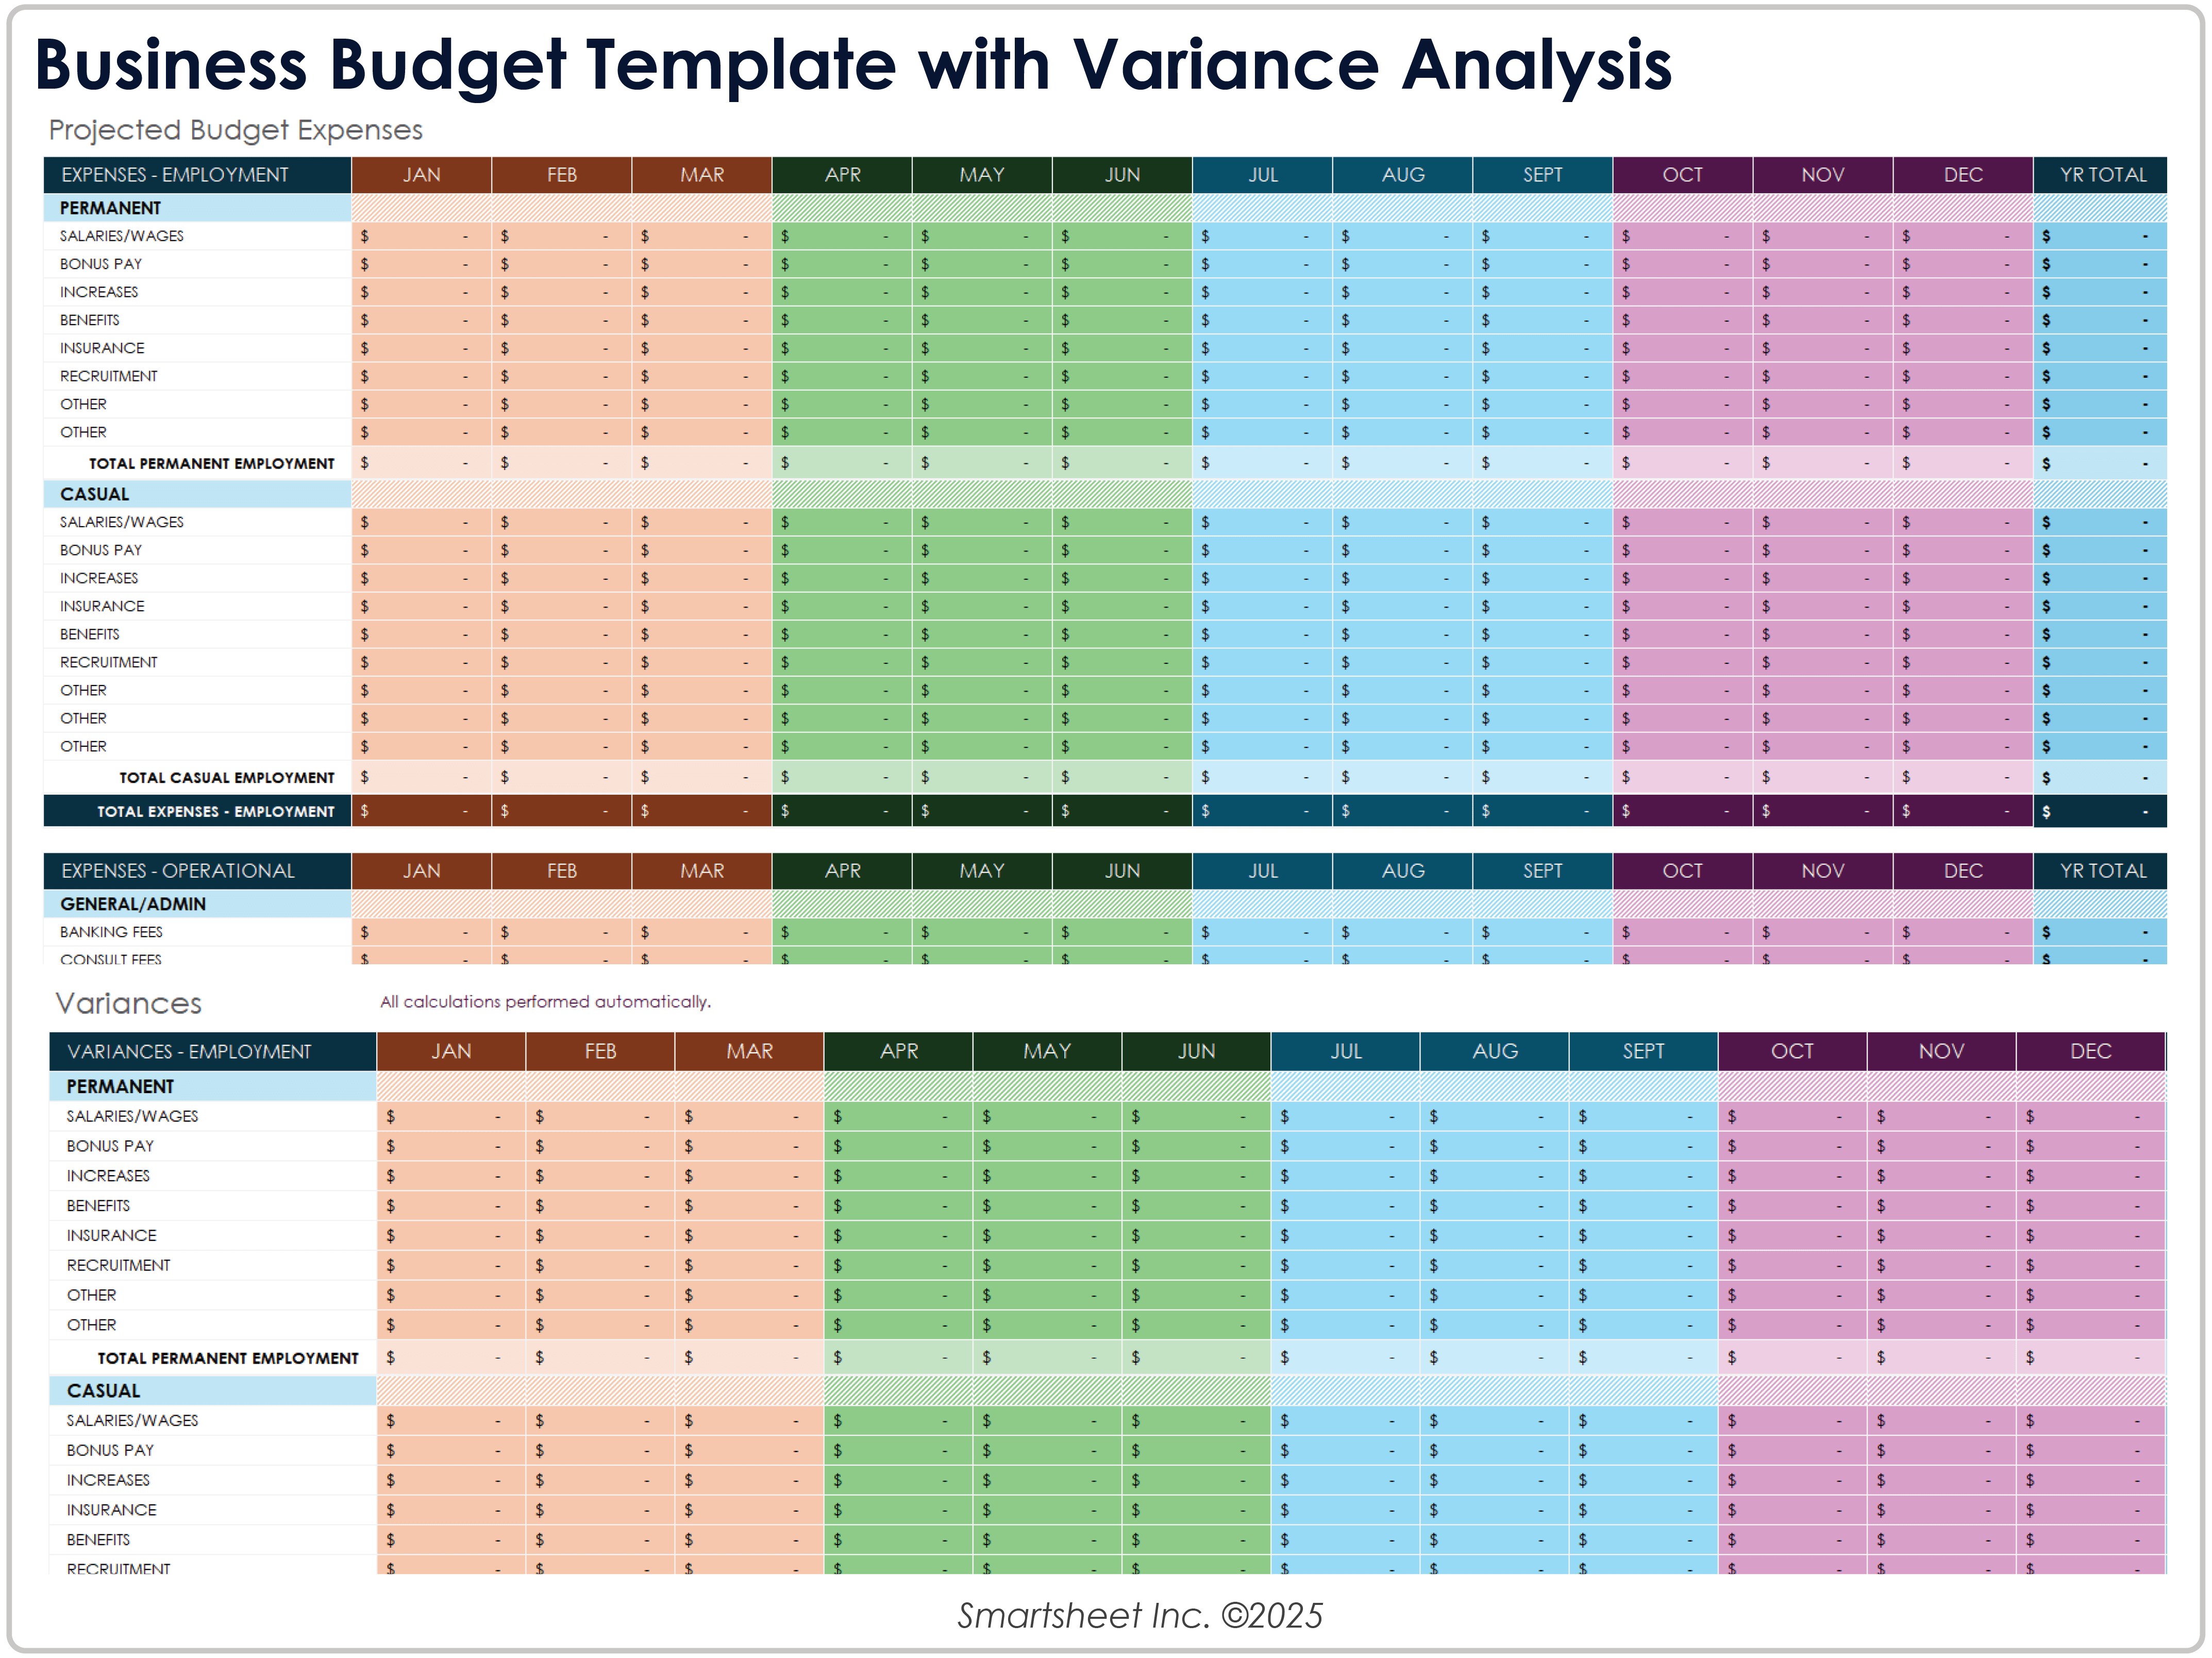
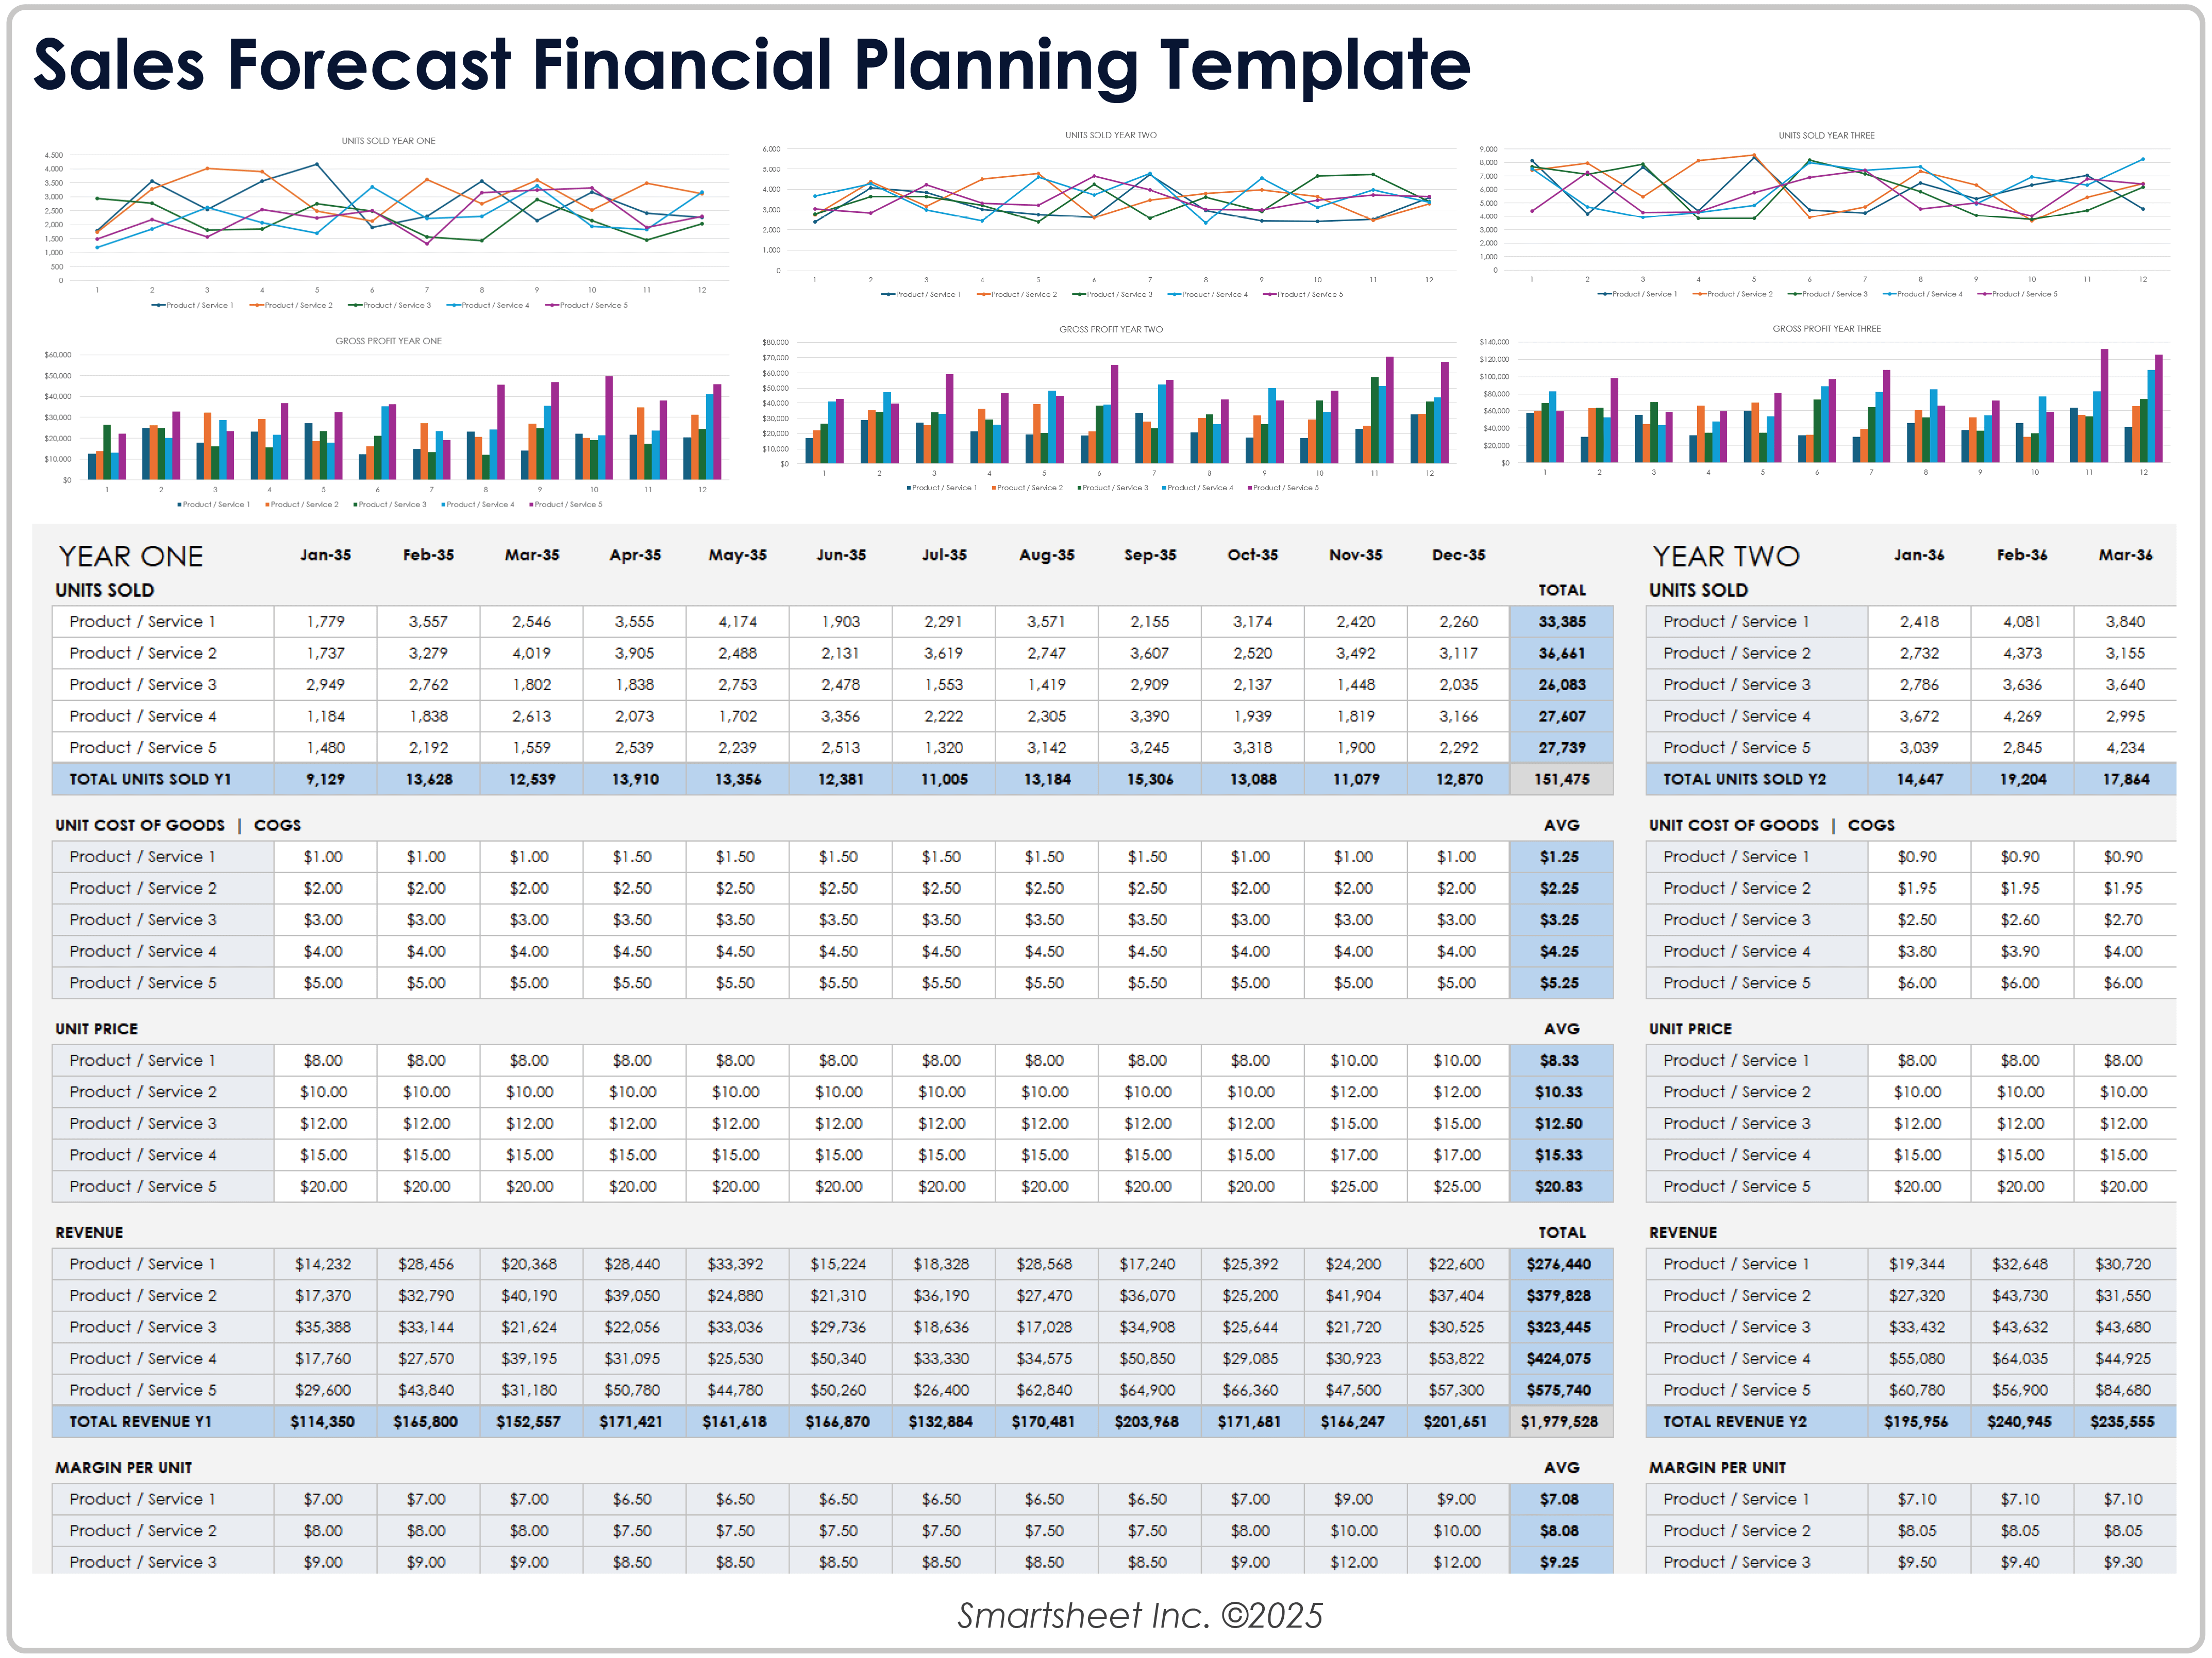
Revenue is one of the most influential assumptions in a business-oriented financial long term Template. A simple model might begin with total annual sales, but a more useful model breaks revenue into products, services, customer groups, units, prices, or other meaningful drivers. This allows the forecast to explain where growth comes from instead of simply applying an arbitrary percentage to the previous year.
For personal planning, income can be divided into salary, business income, rental income, interest, dividends, pensions, or other recurring sources. Each source should have its own assumptions when the timing or growth behavior differs. A salary increase may follow a different pattern from investment income, and a temporary consulting payment should not automatically be treated as recurring income for the entire planning horizon.
Revenue assumptions should also be tested for internal consistency. If unit sales increase rapidly, the model should consider whether production capacity, staffing, inventory, marketing expenditure, or working capital must also increase. For personal income, a higher income assumption may influence taxes, savings capacity, lifestyle spending, and investment contributions. The objective is to build a connected model rather than a collection of optimistic figures.
Forecasting expenses realistically
Expense forecasting works best when costs are separated into meaningful categories and linked to realistic drivers. Fixed costs may remain relatively stable over a period, while variable costs may rise with sales, production, staffing, or usage. Some expenses occur annually or irregularly, so a monthly view alone can make them appear more volatile than they really are. A long-term plan should account for both recurring and exceptional costs.
For a business, common categories include payroll, rent, utilities, marketing, professional services, insurance, technology, inventory, maintenance, taxes, interest, and capital expenditure. For personal planning, categories may include housing, transportation, food, insurance, education, healthcare, travel, debt service, savings, and investment contributions. Categories should be detailed enough to support decisions but not so detailed that maintaining the model becomes burdensome.
Inflation and cost escalation should be treated as assumptions rather than hidden adjustments. If an expense is expected to increase, record the reason and the rate used. This makes later revisions easier. It is also wise to identify expenses that are discretionary, because these may become adjustment levers when income or cash flow falls below expectations.
Cash flow is different from profit
One of the most important principles in a long-term financial plan is the distinction between profitability and cash availability. A business can show accounting profit while experiencing a cash shortage because customers pay slowly, inventory requires funding, debt payments are due, or capital purchases consume cash. A household can have strong income but limited available cash because savings contributions, debt payments, or large planned purchases absorb much of the monthly surplus.
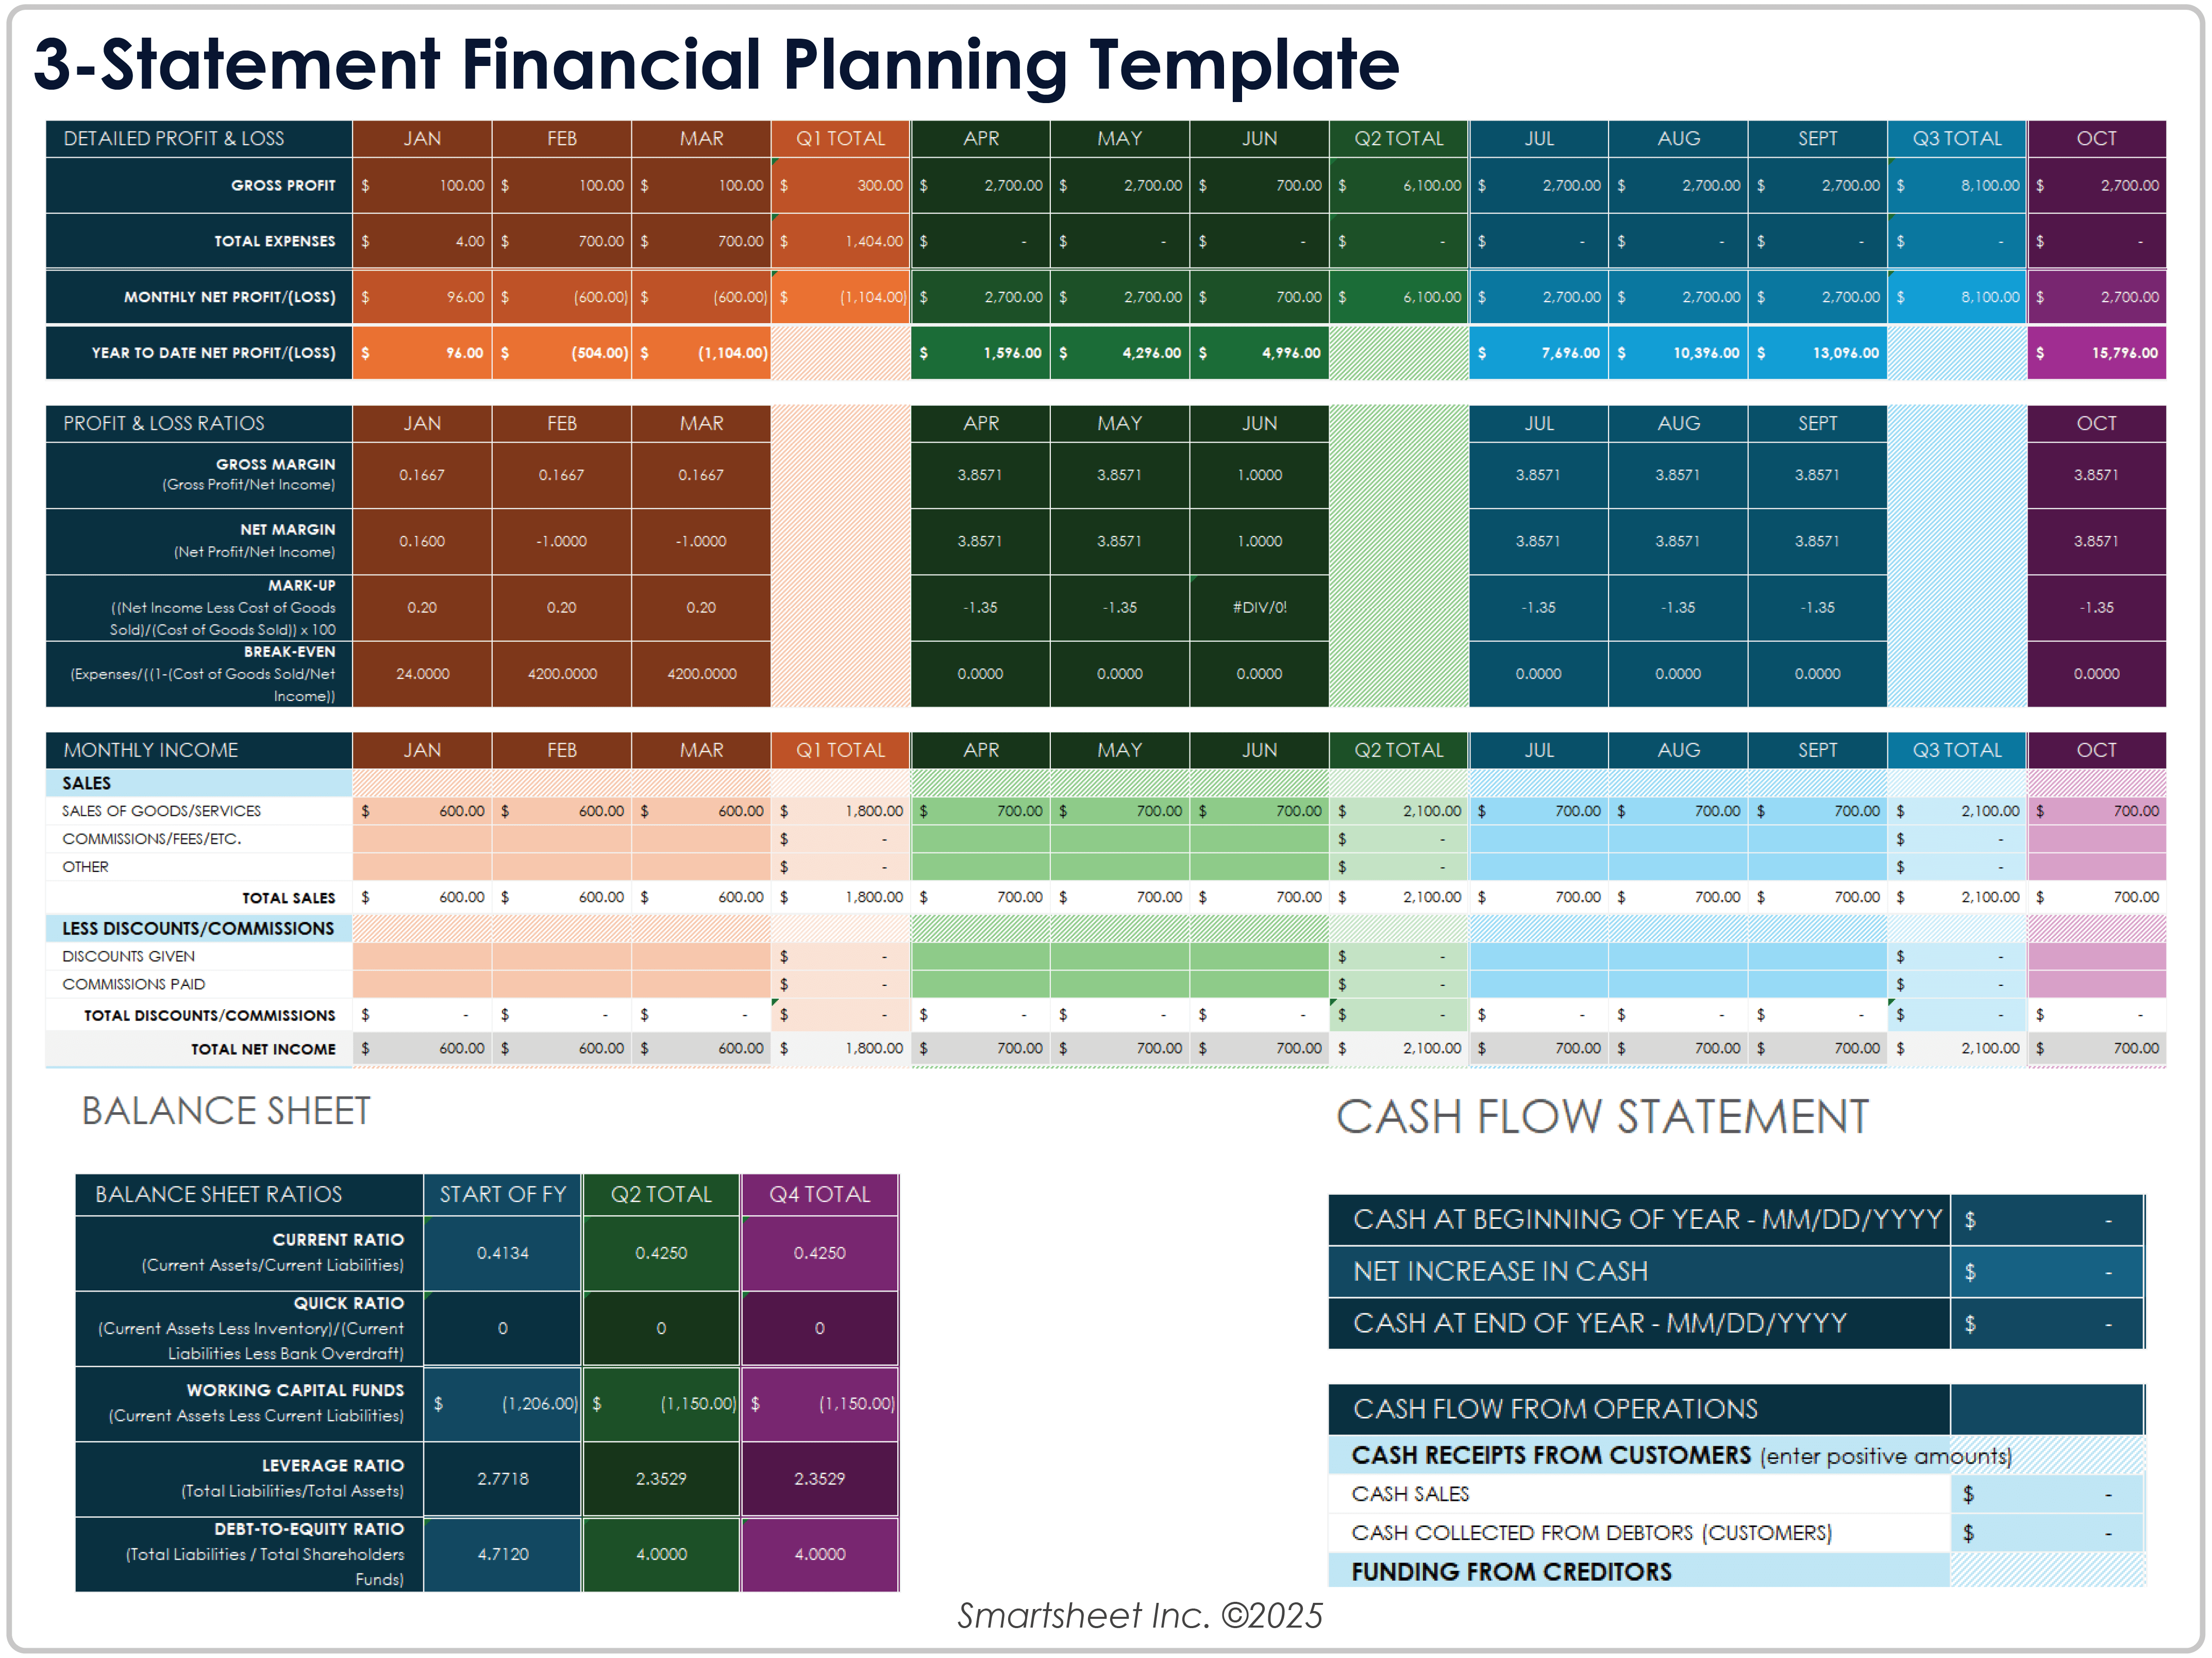
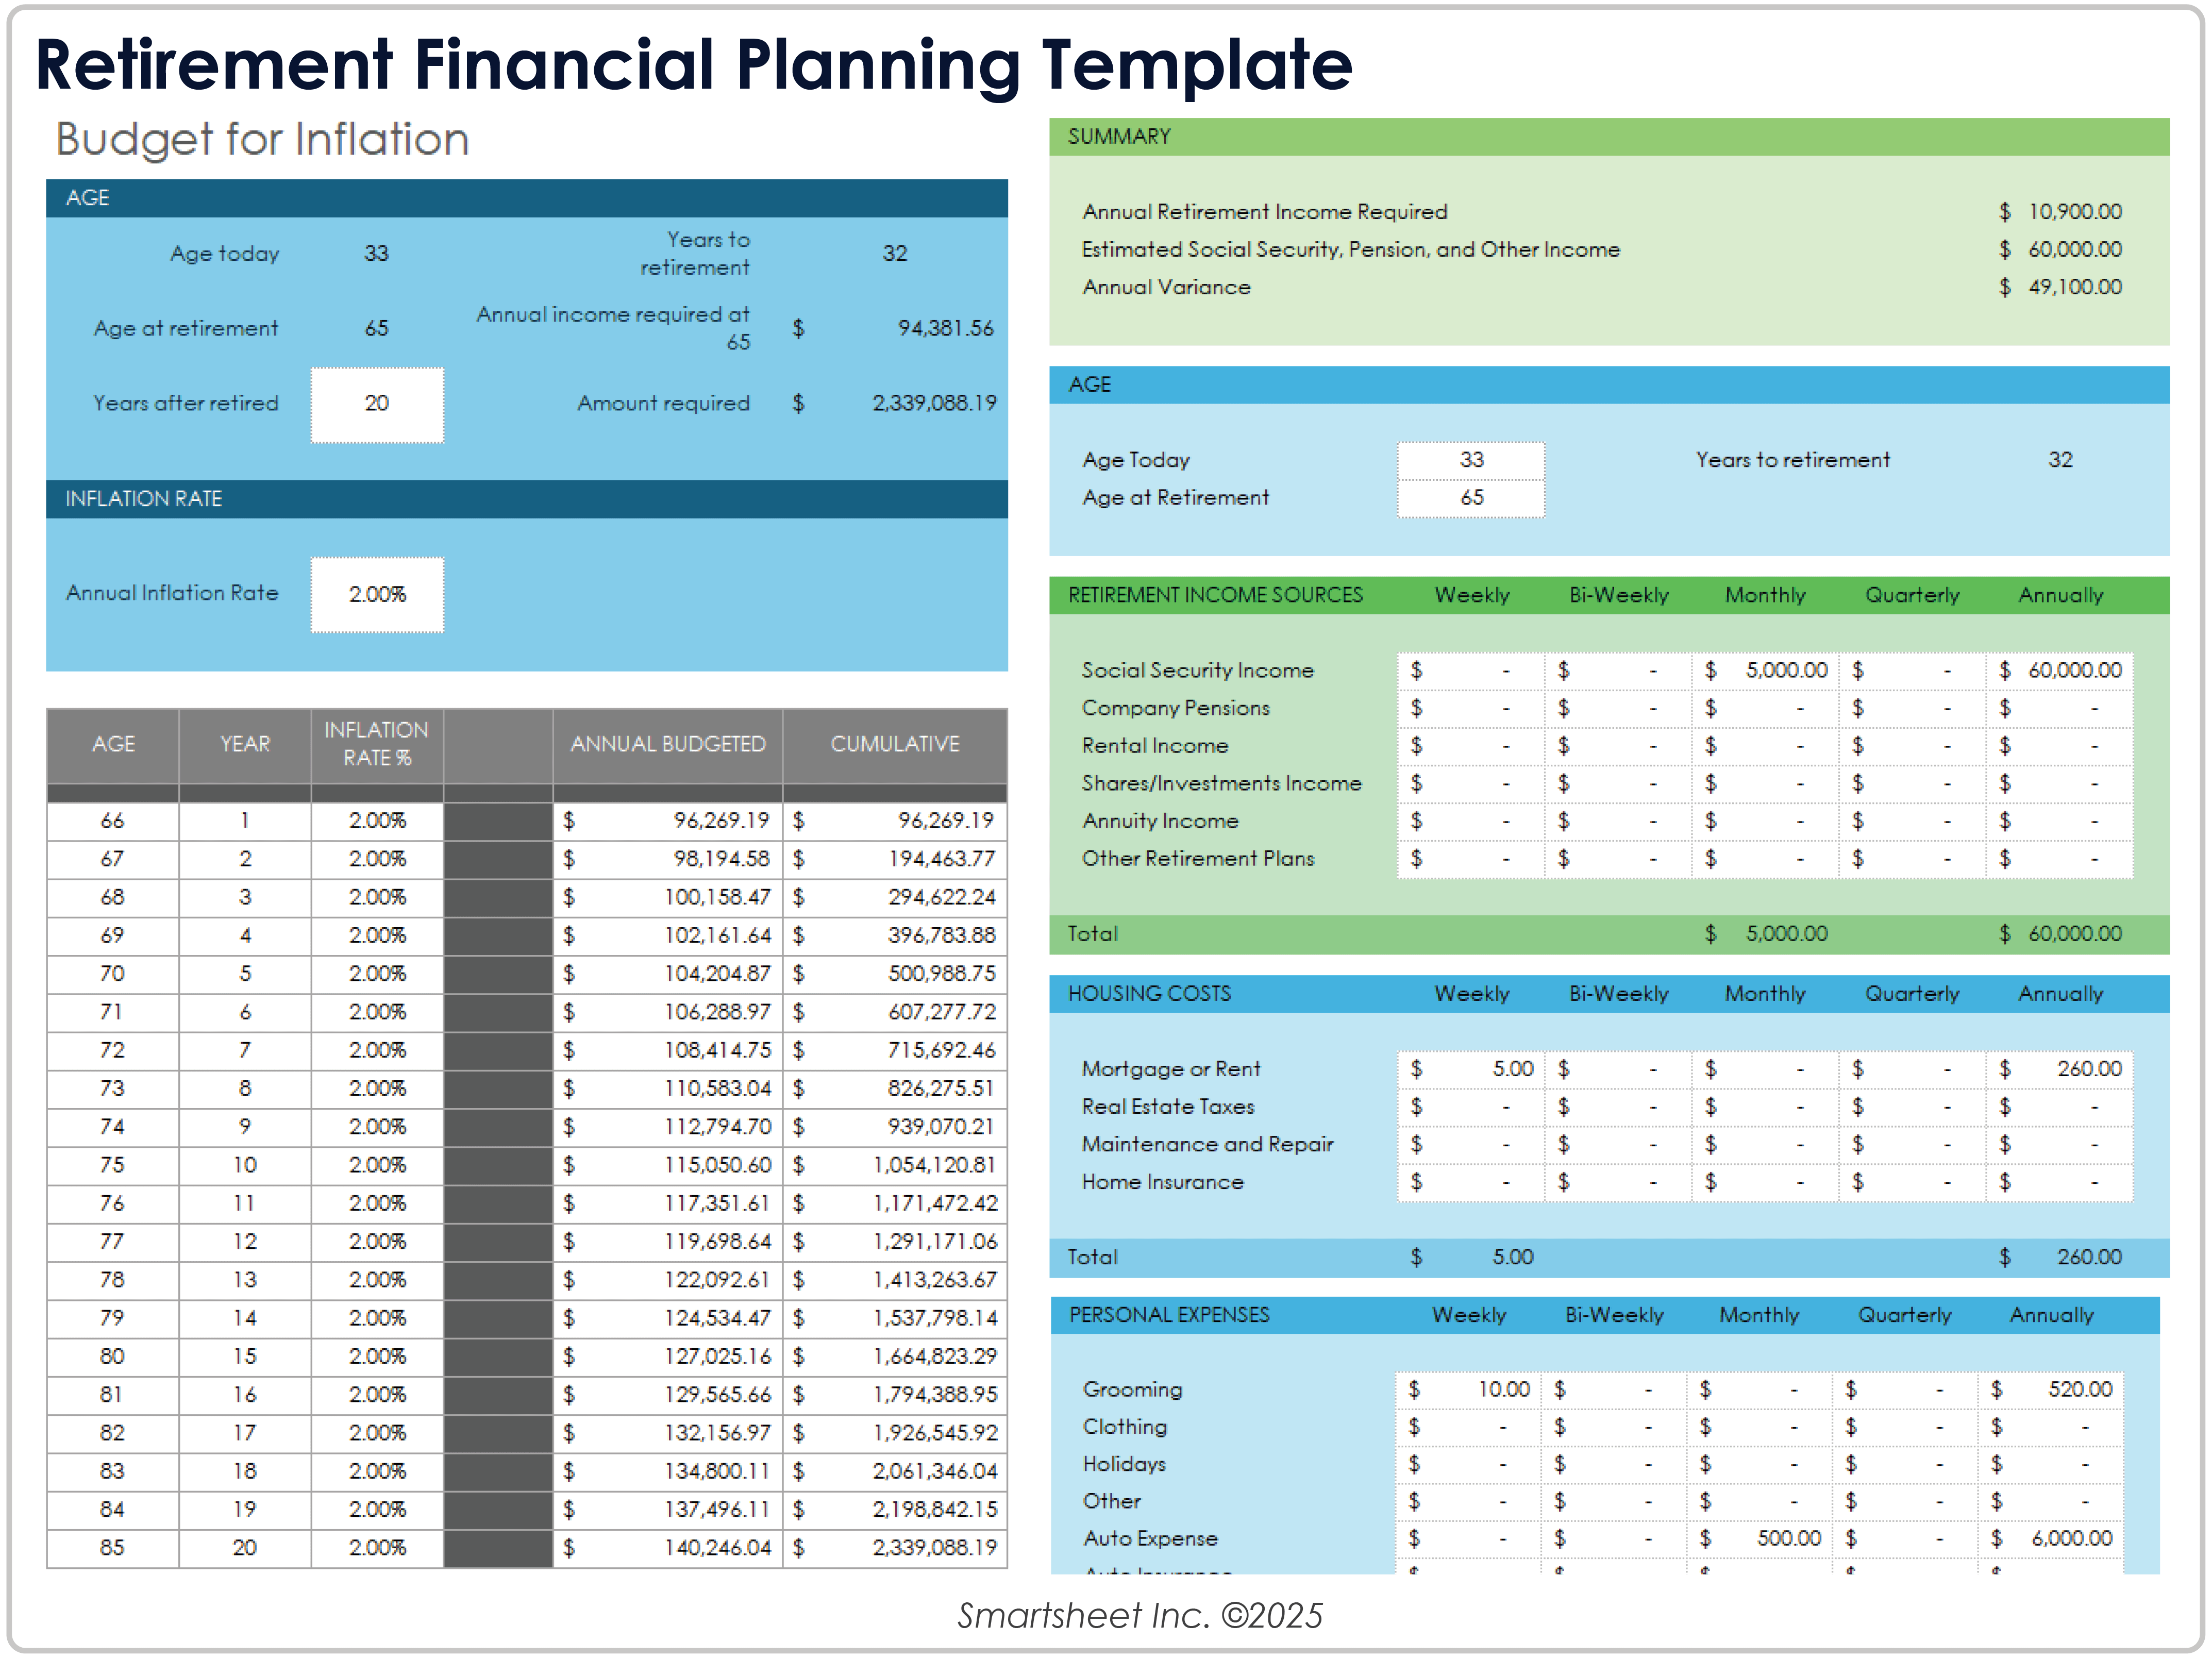
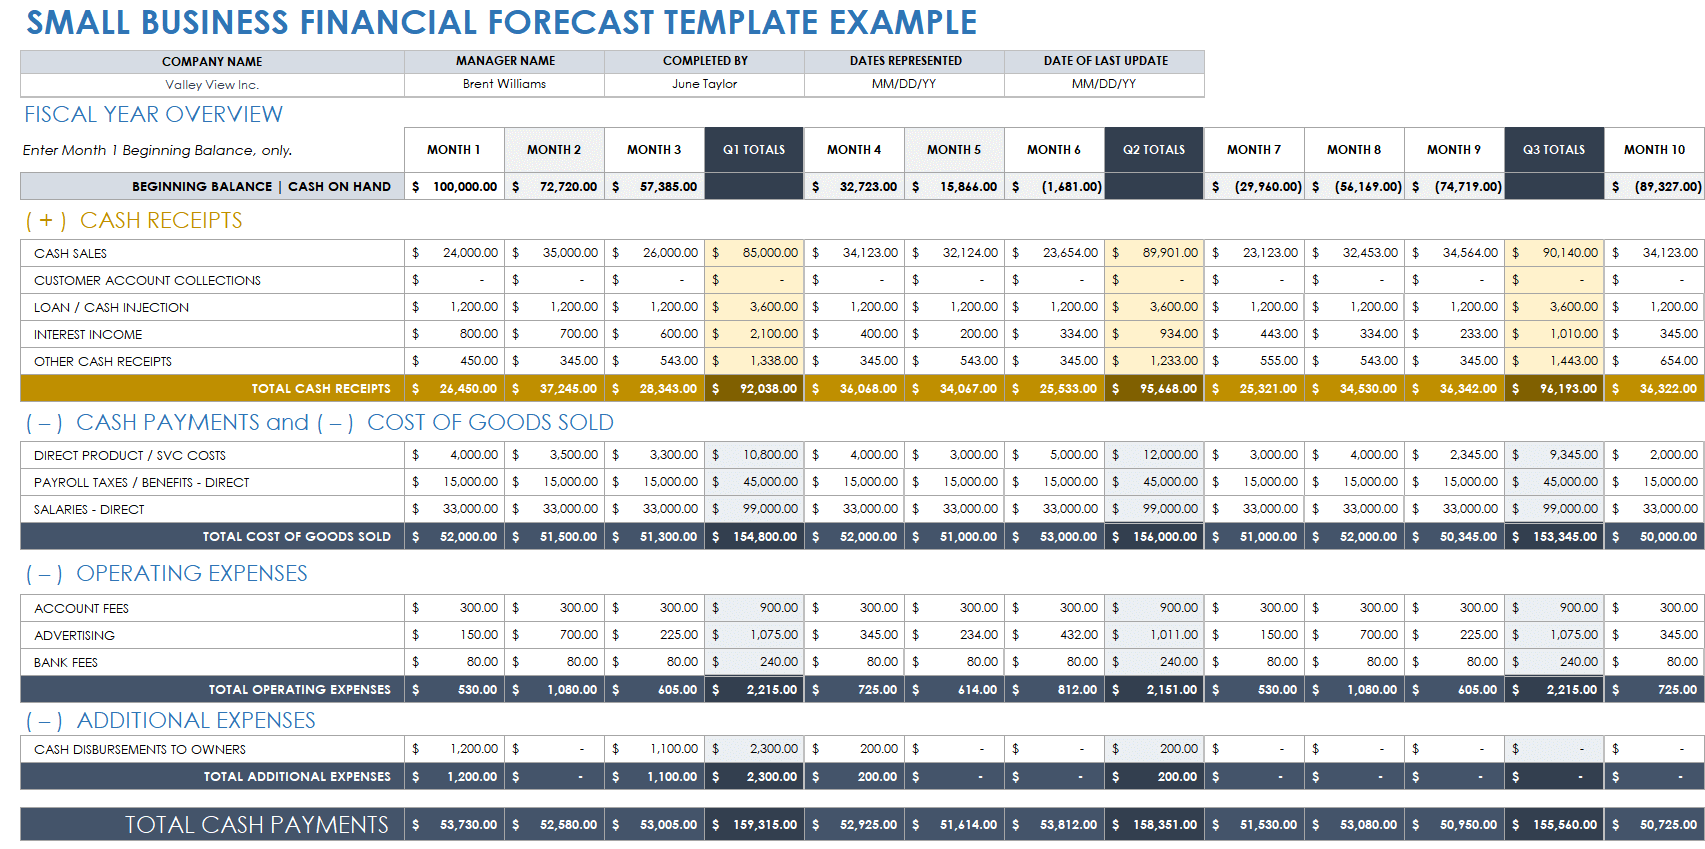
A cash-flow section should therefore show opening cash, cash inflows, cash outflows, and ending cash. Business models commonly separate operating, investing, and financing activities. Personal models can use a simpler structure that separates income, regular spending, savings, investments, debt payments, and major purchases. The goal is to reveal when liquidity could become tight.
Cash-flow projections are especially valuable when the timing of events matters. A business may need funding before a new project produces revenue. A household may need to accumulate a cash reserve before purchasing property. By placing these events on the same timeline, the model can reveal whether the planned action is financially feasible under the chosen assumptions.
Using the balance sheet and net worth view
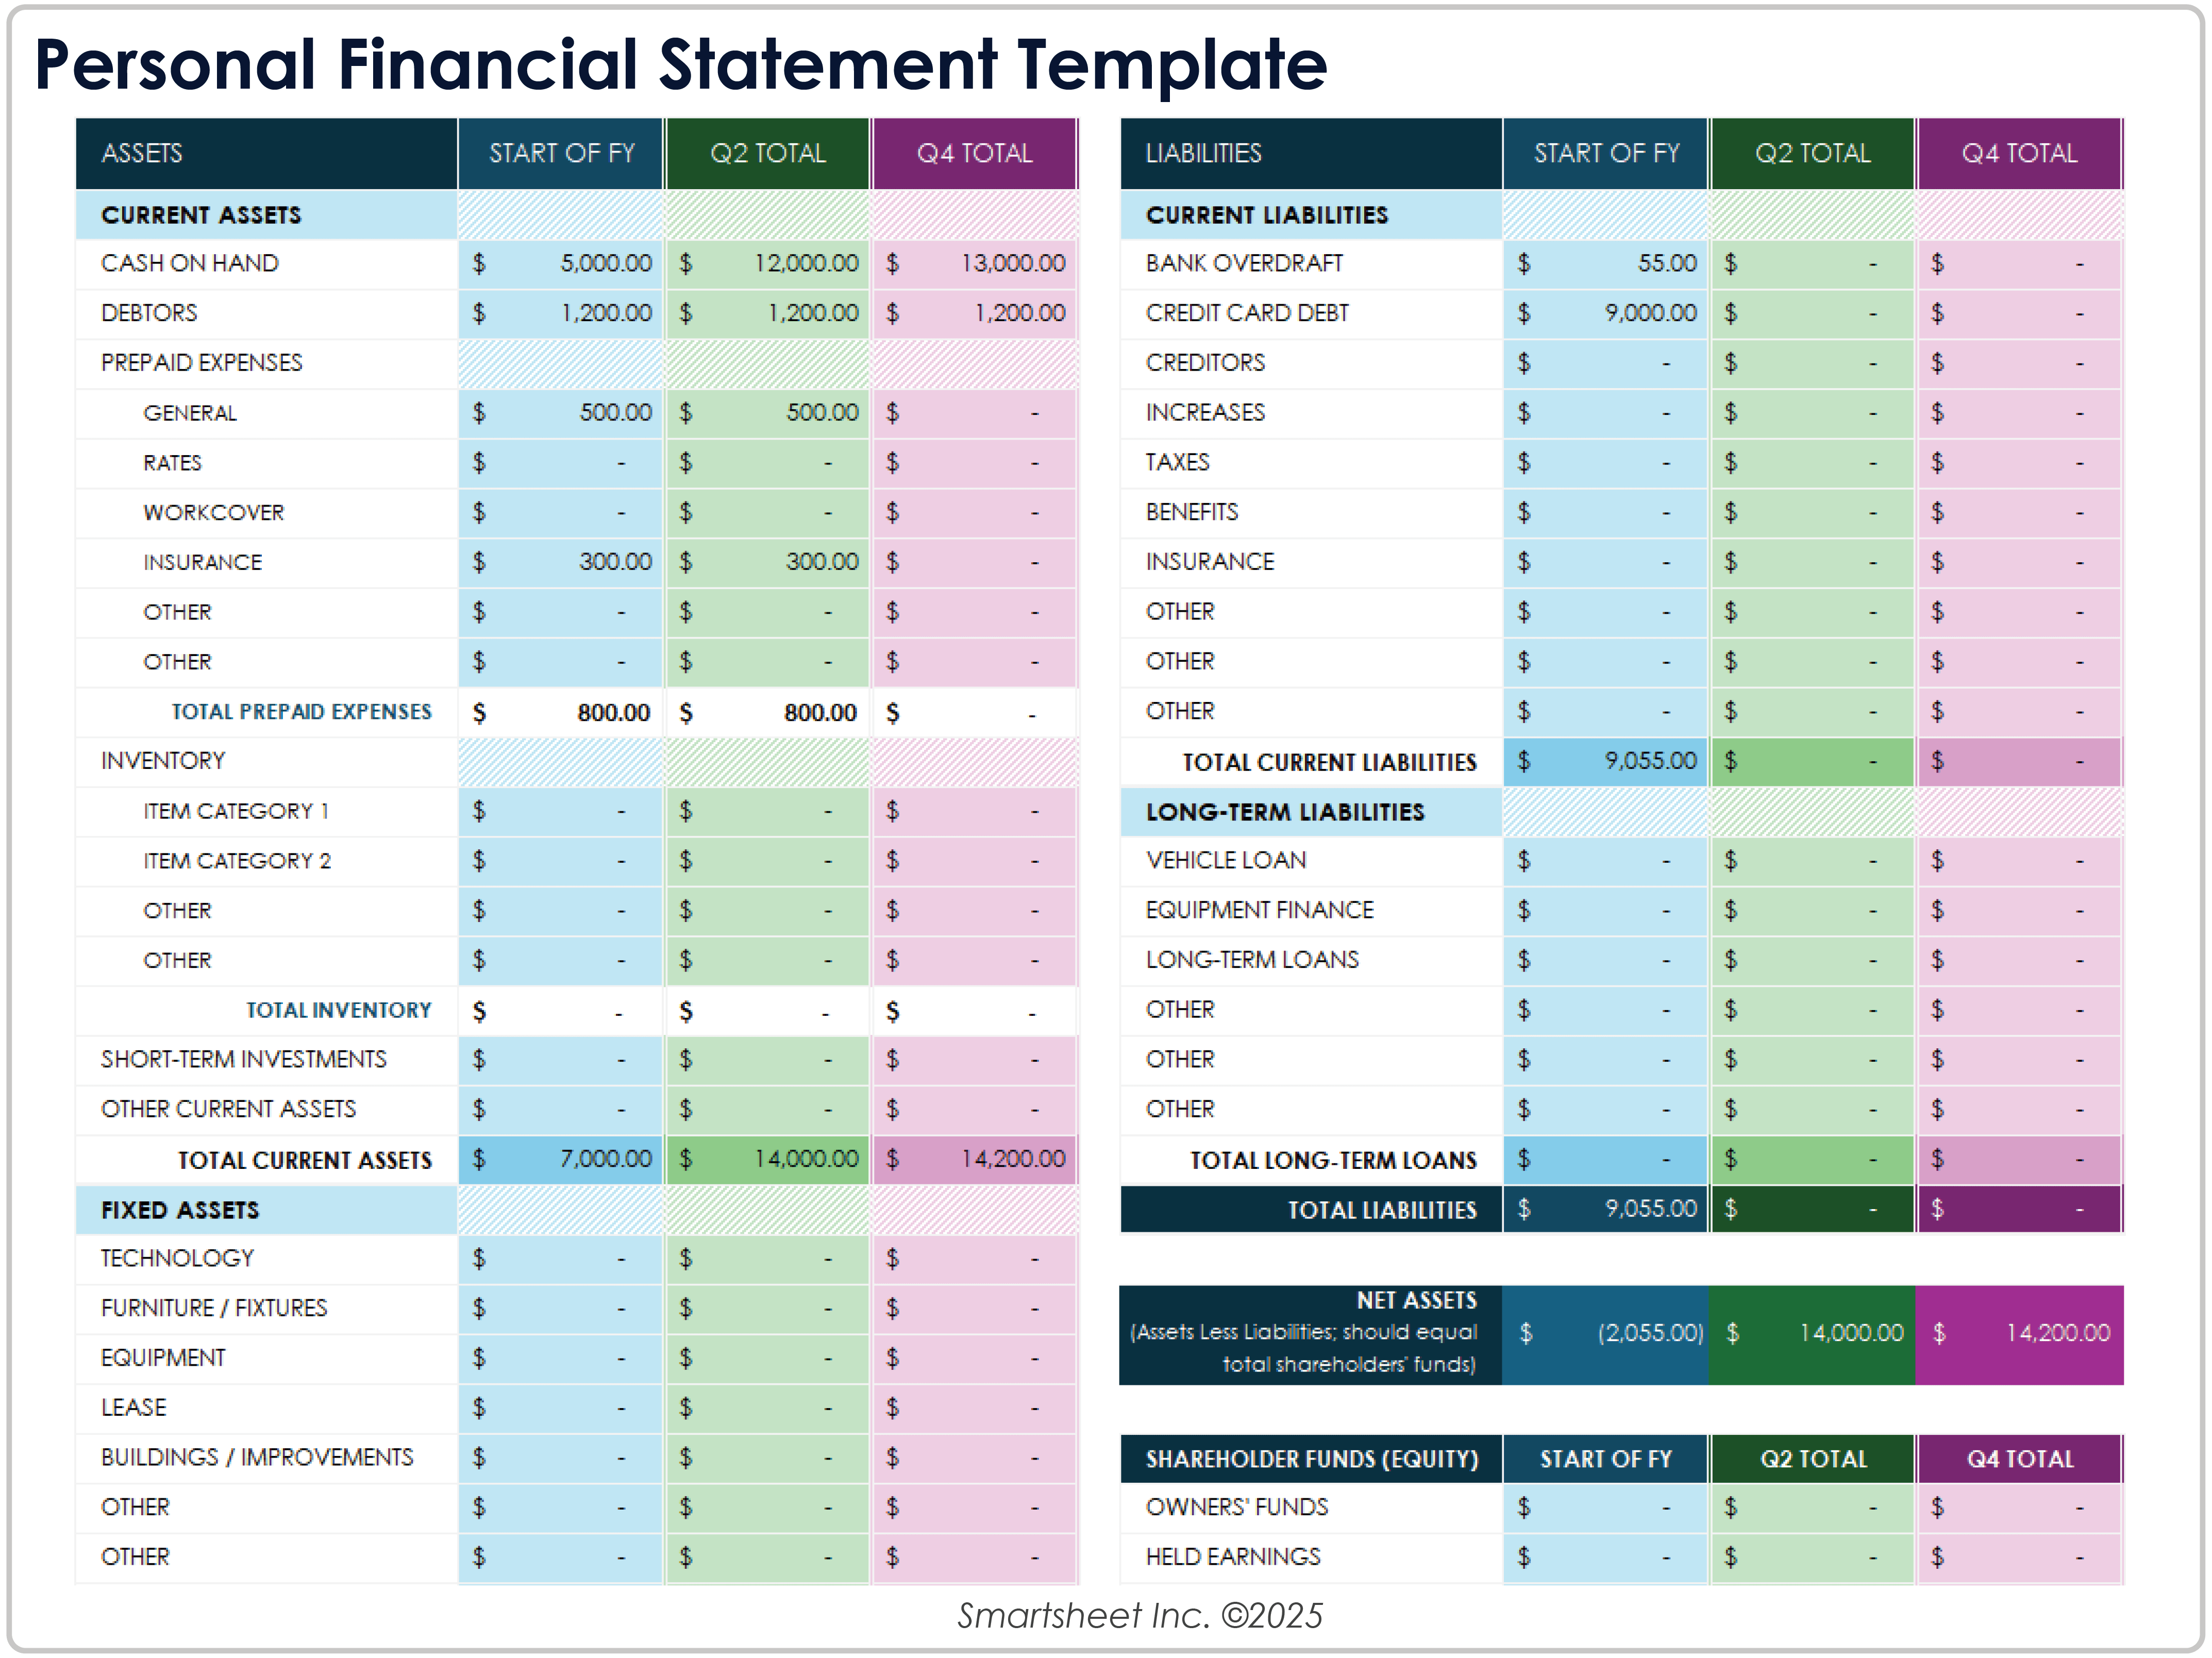
A long-term plan becomes more informative when it shows how the financial position changes, not just how much money comes in and goes out. For businesses, this means tracking assets, liabilities, and equity. For individuals, the equivalent concept is often expressed through assets, debts, and net worth. The balance-sheet view helps reveal whether growth is being supported by accumulated resources, new borrowing, or additional capital.
Net worth is particularly useful for personal planning because it provides a high-level measure of financial position. A household may have increasing income but little improvement in net worth if spending and debt are also increasing. Conversely, a period of heavy investment may reduce available cash while increasing long-term assets. The model should therefore show the components behind the headline number.
The same logic applies to a business. Revenue growth does not automatically mean financial strength. Receivables, inventory, debt, fixed assets, and working capital can all change at the same time. A connected financial model makes these relationships visible and helps the user ask better questions before committing to a major decision.
Personal planning versus business planning
A personal long term financial plan usually focuses on financial security and life goals. Typical objectives include building emergency reserves, reducing debt, purchasing property, funding education, investing for long-term wealth, and preparing for retirement. The model should reflect personal cash flow and realistic changes in income and spending rather than treating the household like a corporation.
A financial long term template for business needs a different level of operational detail. Revenue may depend on units sold, prices, customer growth, capacity, or contracts. Expenses may depend on employees, facilities, inventory, marketing, financing, and capital expenditure. The model may also need to show profitability, cash requirements, balance-sheet changes, and funding needs over multiple years.
The distinction does not mean that the two models are unrelated. Both benefit from the same principles: define the starting position, state assumptions, connect inputs to outputs, test scenarios, establish measurable goals, and review the plan regularly. The difference is mainly in the categories, drivers, and level of financial detail required.
Excel, spreadsheet, and document formats
People searching for a financial long term template excel free option are usually looking for a structured workbook that can calculate projections automatically. A spreadsheet is particularly useful when the plan contains formulas, scenario calculations, monthly details, or connected financial statements. Excel is also useful when the model needs advanced formulas or extensive financial schedules.
A financial long term template google sheets format is useful when several people need to review the same planning model or when the user prefers a browser-based spreadsheet. The essential design principles remain the same: assumptions should be separated from calculations, formulas should be consistent, and important outputs should be easy to inspect. A collaborative spreadsheet can also make review cycles easier when multiple decision-makers contribute.
A document-oriented structure, such as a financial long term template google docs format, is better when the primary goal is explaining the plan rather than calculating it. A document can contain objectives, assumptions, milestones, policies, narrative explanations, and selected financial summaries. For a detailed numerical model, however, a spreadsheet usually works better as the calculation layer, with a document used for the narrative layer.
How to build the template step by step
Step one is to define the purpose. Decide what decision the model needs to support. A retirement plan, a property purchase, a business expansion, a debt reduction strategy, and an investor forecast require different structures. Write the main objective at the top of the model and define the time horizon before entering detailed numbers.
Step two is to establish the starting position. Use current and reasonably reliable financial information for the opening period. For a business, reconcile the starting cash, debt, assets, liabilities, revenue, and expenses with the organization’s records. For personal planning, list major income sources, recurring expenses, savings, investments, debts, and significant assets. The model becomes unreliable if its starting point is not credible.
Step three is to build the assumptions area. Keep key assumptions in one clearly labeled section. Examples include annual income growth, price growth, inflation, expected investment return, savings contributions, staffing growth, rent increases, debt interest, tax assumptions, and planned capital purchases. Avoid hiding assumptions inside formulas because doing so makes the model harder to understand and maintain.
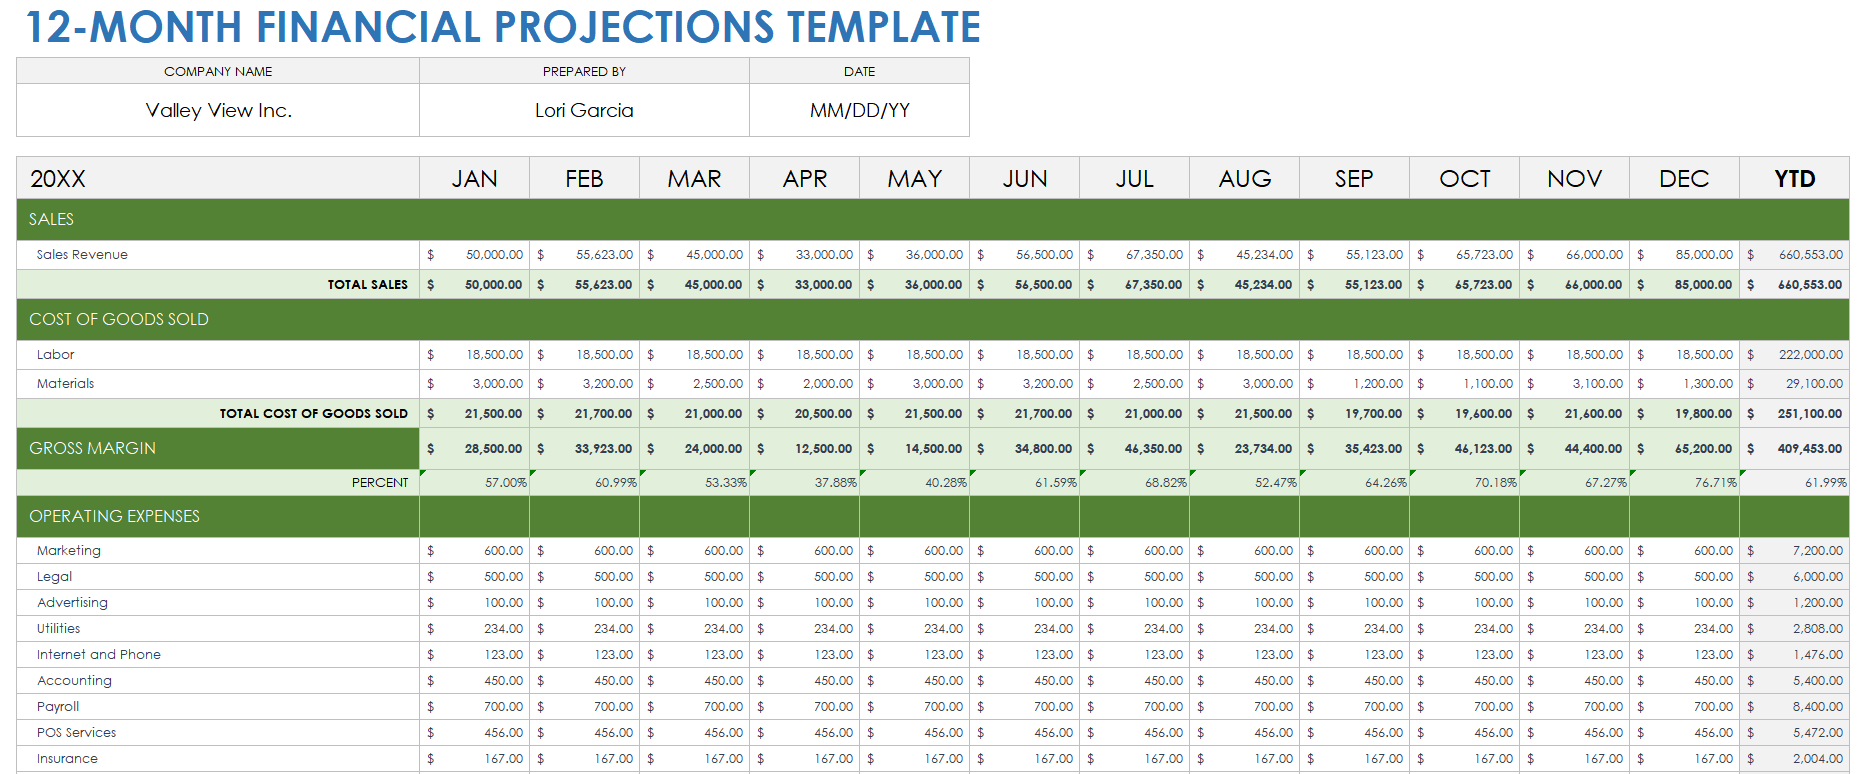
Step four is to create the annual forecast. Build rows for the major financial categories and columns for each year. Where detail matters, create a monthly or quarterly schedule underneath the annual summary. Keep formulas consistent across periods. If Year 2 revenue is calculated from Year 1 revenue and a growth assumption, the same logic should generally continue through the remaining periods unless a documented change is intended.
Step five is to connect the financial statements or personal summaries. Business models can link income, cash flow, and balance-sheet projections. Personal models can connect income and spending to savings, investments, debt, and net worth. The objective is to prevent conflicting numbers. For example, cash used for a major purchase should appear as an outflow and should also affect the relevant asset or cash balance.
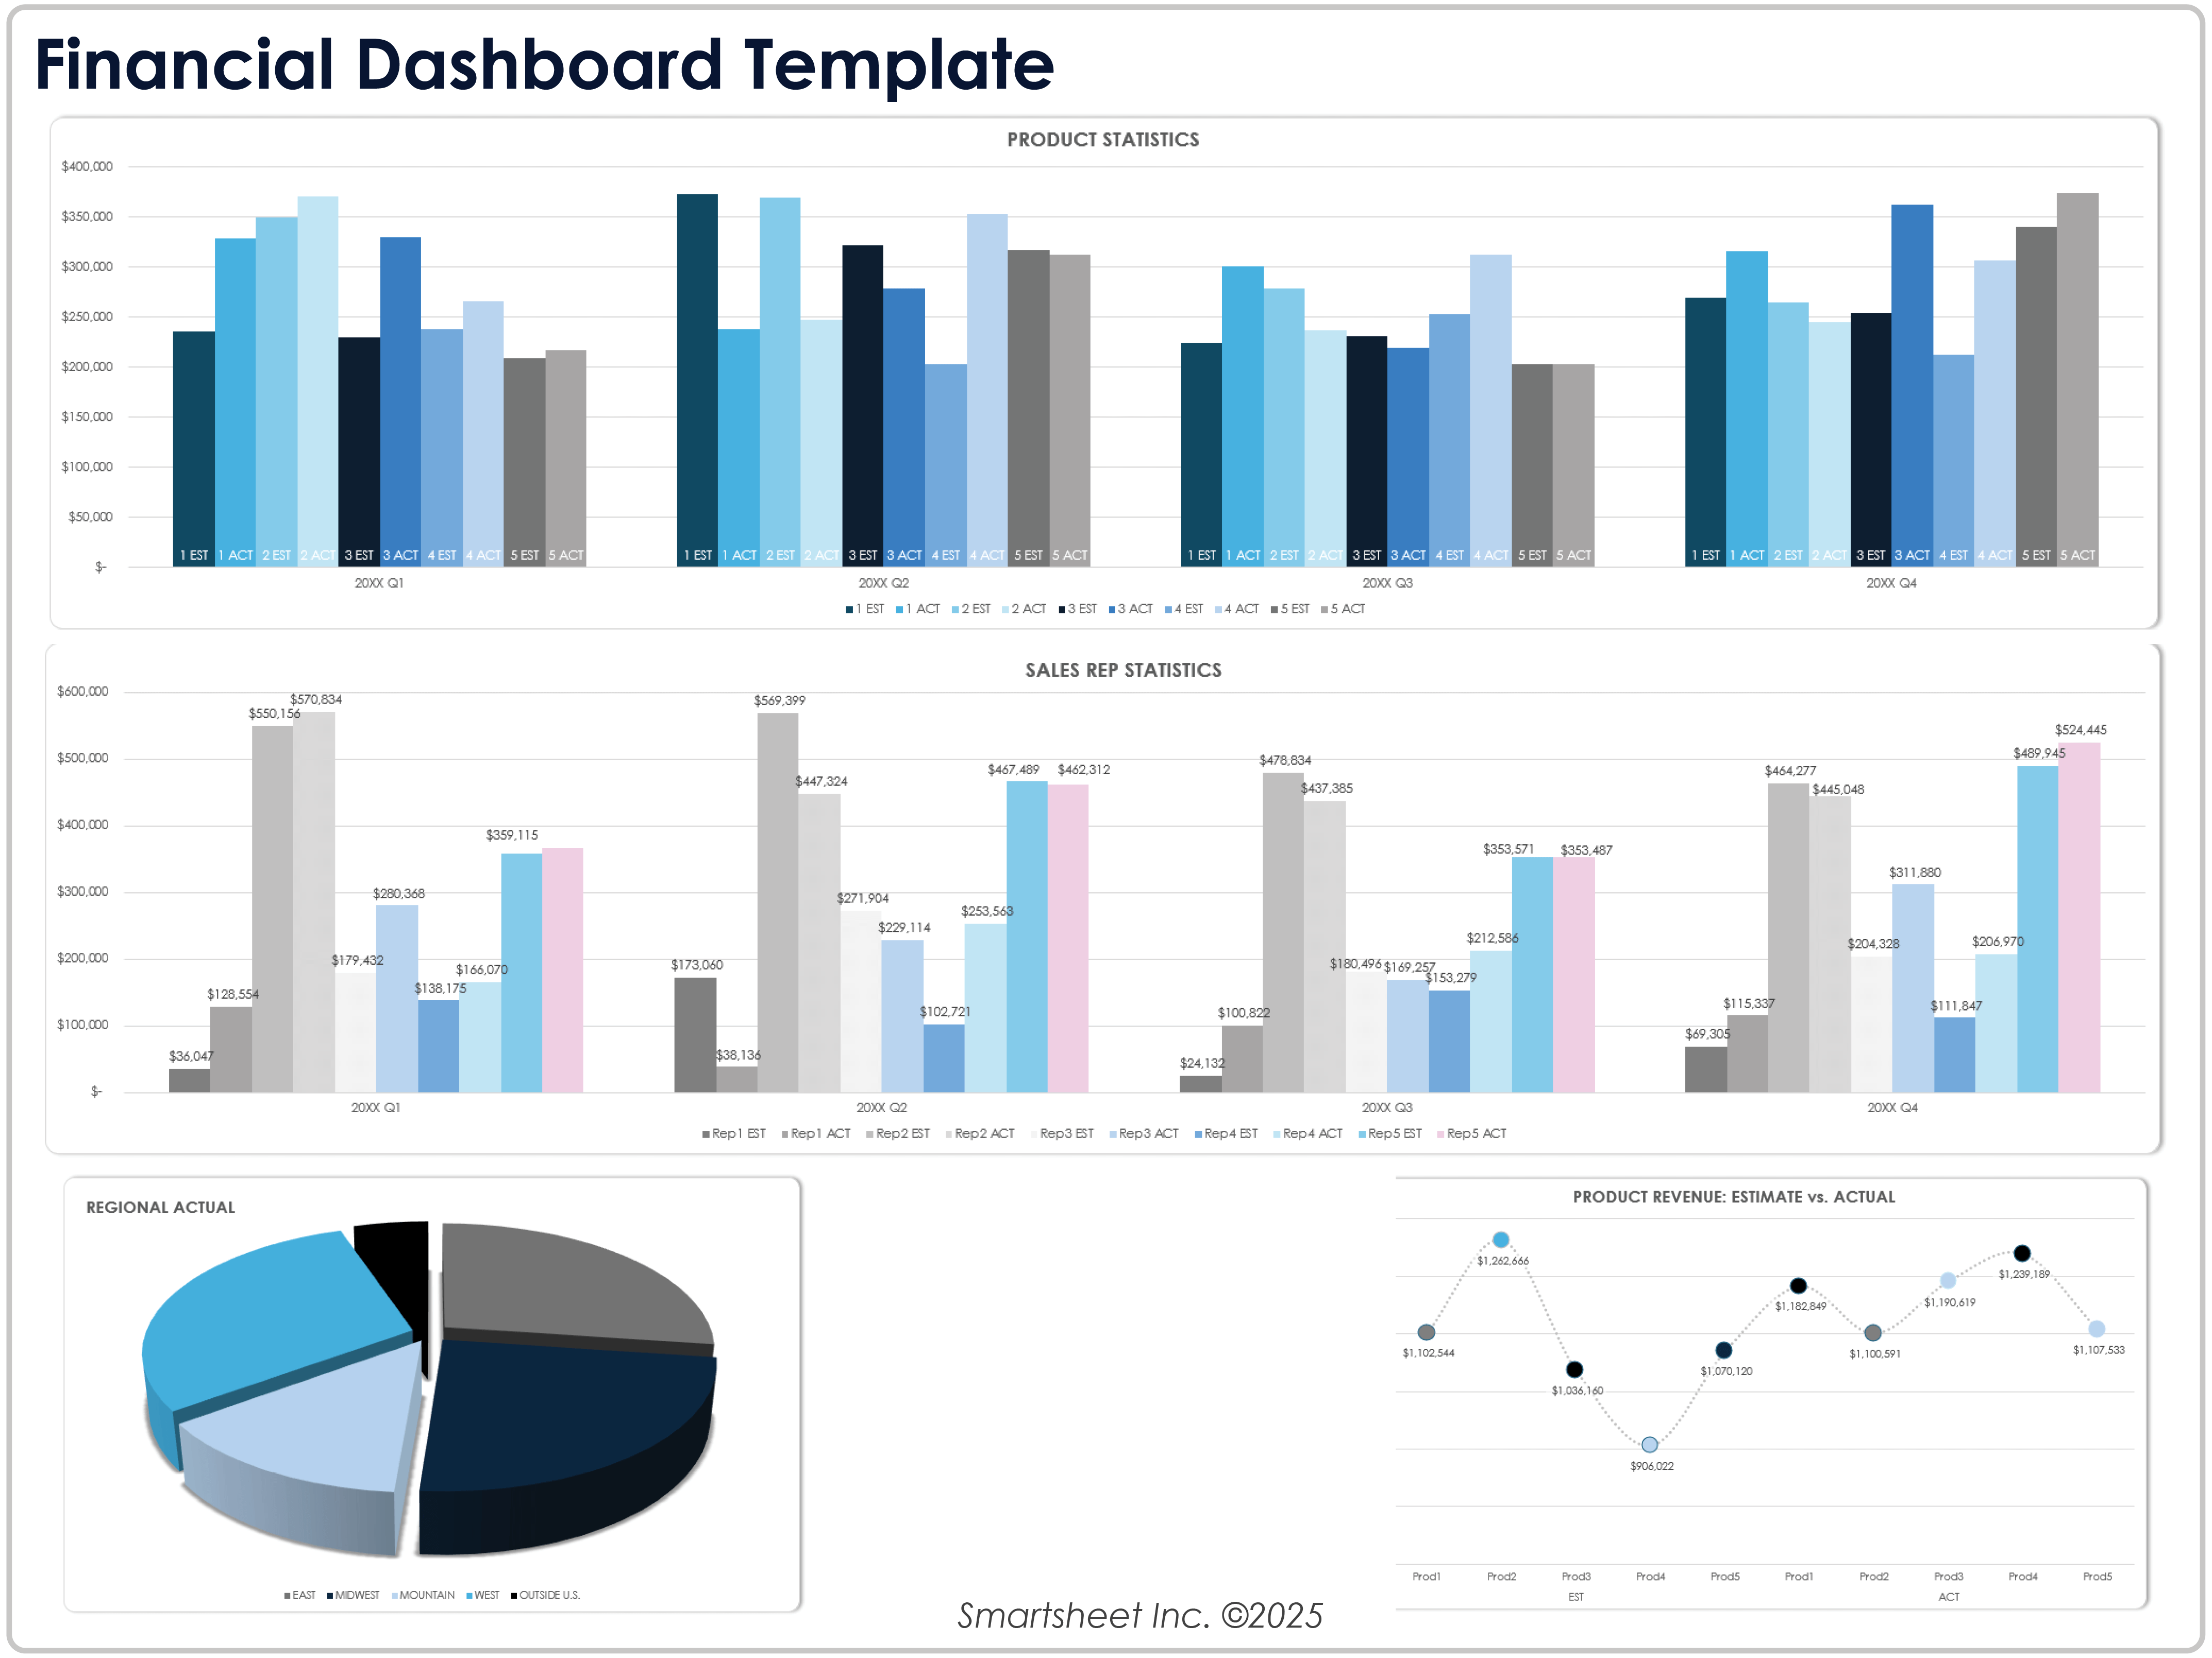
Step six is to add decision metrics. Choose a small number of indicators that directly relate to the purpose of the plan. These may include operating margin, ending cash, debt balance, savings rate, investment balance, net worth, funding requirement, break-even point, or progress toward a target. Too many indicators can obscure the important signals.
Step seven is to test the model. Change one assumption at a time and confirm that the expected outputs respond logically. Then test combinations of assumptions. If a small change in revenue causes an implausibly large change in cash, inspect the formulas. If increasing savings does not reduce available cash, inspect the links between sections.
Step eight is to document the model. Record what each major assumption means, where important figures came from, and when the model was last reviewed. Documentation is especially important when a plan will be used by more than one person or revisited several years later. A clear model should make sense even after the original creator has forgotten the details behind it.
Using scenarios instead of one fixed forecast
A single forecast can create false confidence. A better long-term model usually includes at least a base case and one or two alternatives. For a business, the scenarios might represent stronger sales, slower growth, higher costs, or delayed expansion. For personal planning, scenarios might represent different savings rates, income changes, investment contributions, retirement dates, or major purchase timing.
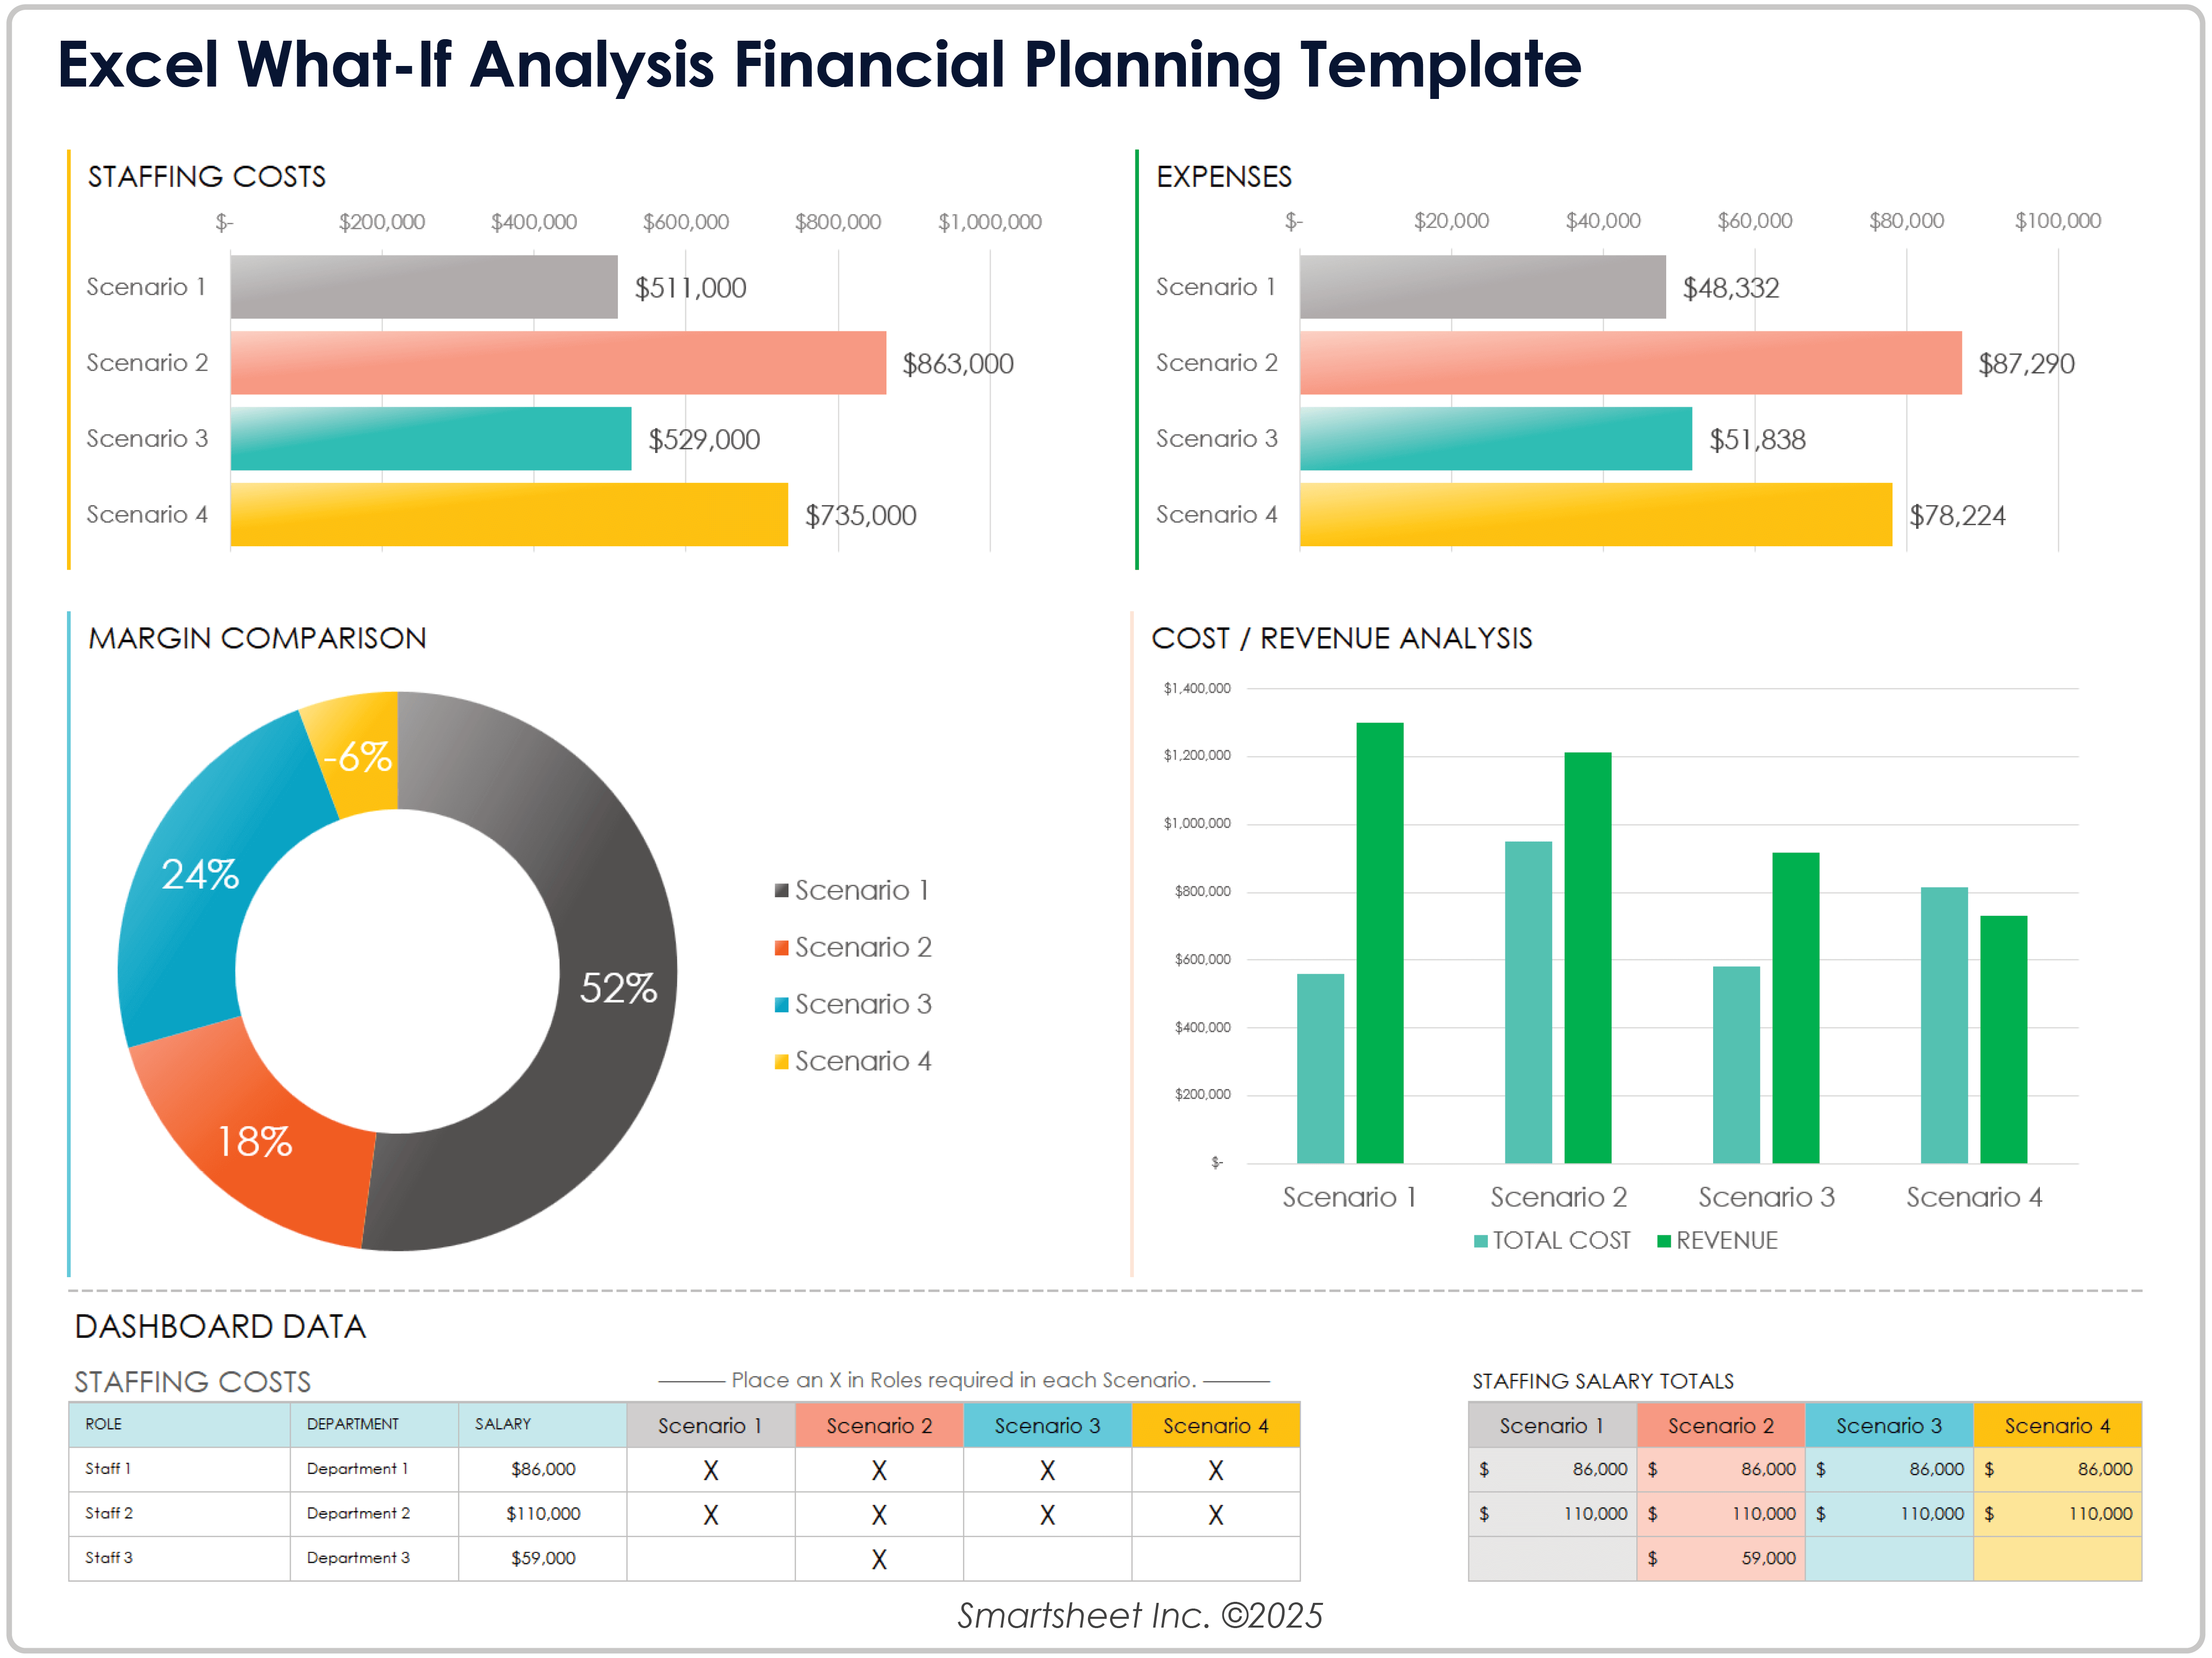
Scenario analysis is most useful when the assumptions are meaningful. Changing every number randomly does not create insight. Instead, identify the variables that could genuinely change the outcome. If revenue depends heavily on customer volume, test customer volume. If a household goal depends on savings contributions, test different contribution levels. If a business is sensitive to staffing costs, model different hiring plans.
The output should emphasize decisions rather than simply ranking scenarios. A weaker scenario may show the minimum cash reserve required to remain stable. A stronger scenario may reveal when an expansion becomes affordable. The purpose is not to predict which scenario will occur but to understand what actions remain sensible under different conditions.
Long-term plans examples that can be modeled
Useful long term plans examples should connect a goal with a measurable financial path. A household might model a property purchase by estimating the required deposit, monthly savings, investment contributions, expected expenses, and purchase date. A business might model expansion by estimating additional sales, staffing, equipment, marketing, working capital, financing, and resulting cash balances.
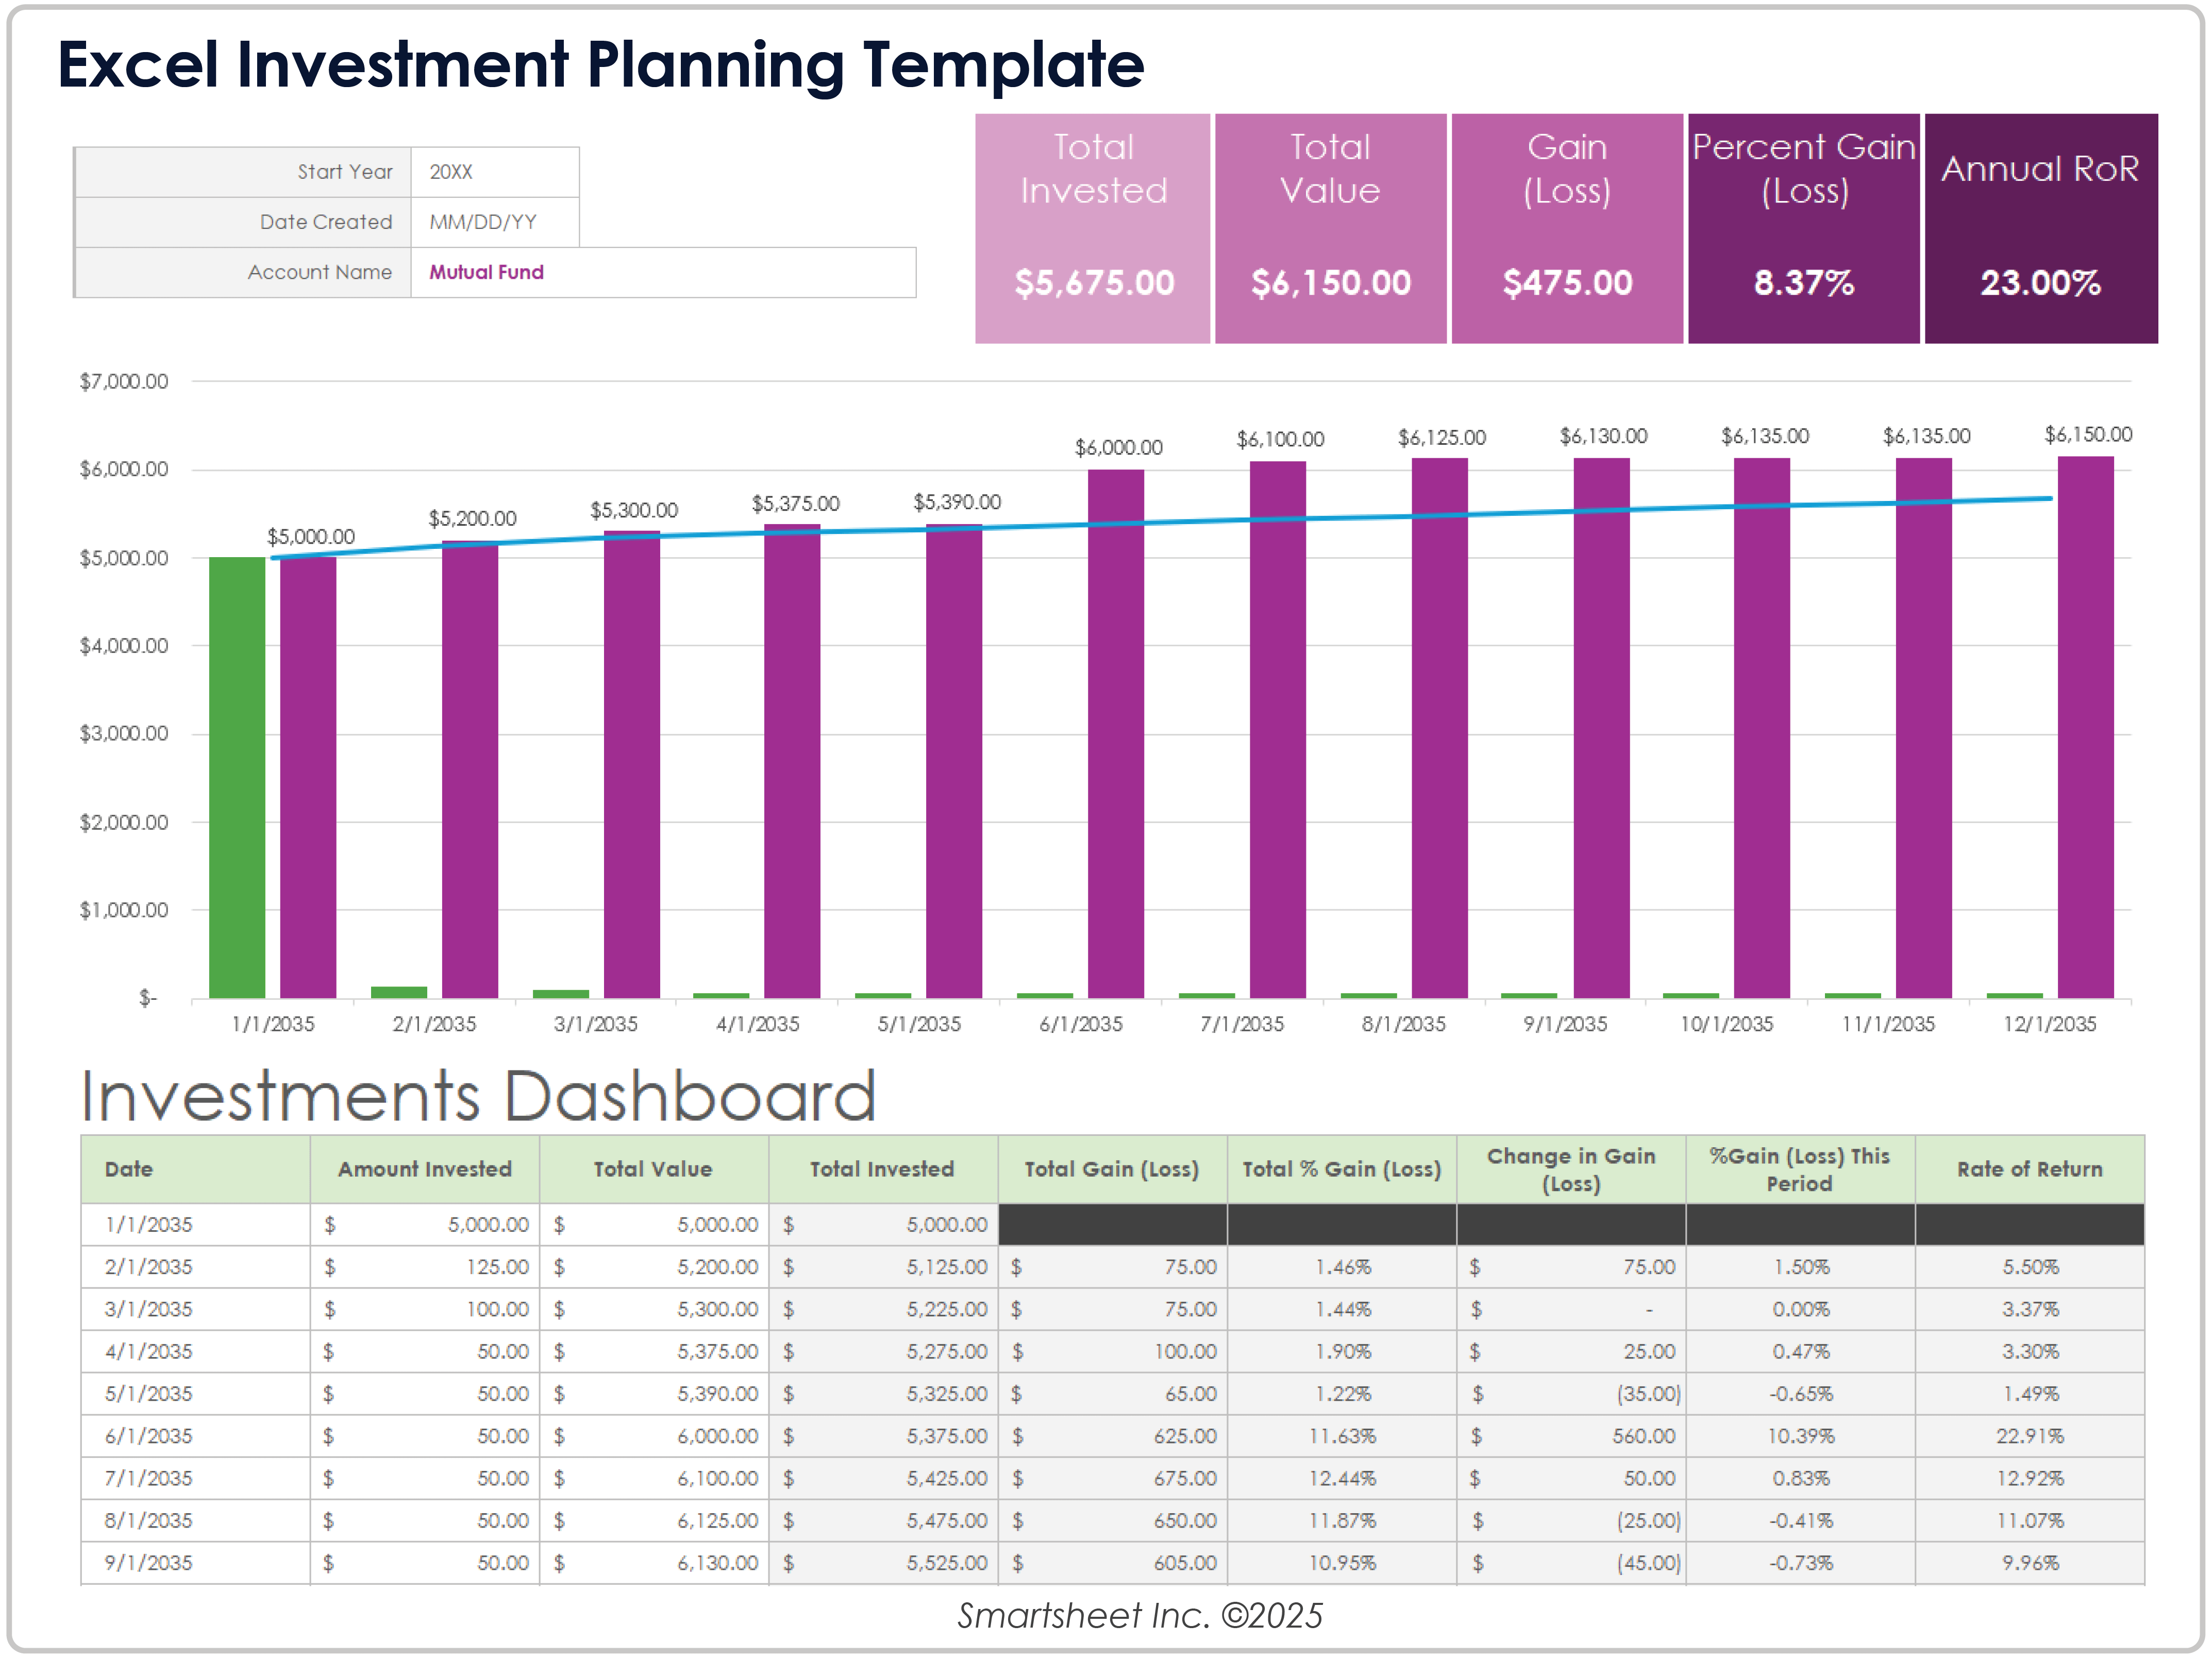
Retirement planning is another common example. The model can begin with current savings and annual contributions, then incorporate a range of return assumptions and projected spending. The important insight is not a single distant balance but the relationship between contribution levels, time, spending needs, and uncertainty. The plan can then be reviewed as actual savings and circumstances change.
Debt reduction can also be modeled over several years. A schedule can show opening debt, interest, required payments, additional payments, and ending balances. The user can compare a standard repayment strategy with an accelerated strategy and examine the effect on cash flow. Similar logic can be applied to business loans, equipment financing, or other long-lived obligations.
Long-term agreements and financial planning are different
A long term agreement template and a financial long-range planning template serve different purposes, even though they can appear together in a business planning process. An agreement defines obligations between parties, such as pricing, services, responsibilities, timing, renewal conditions, or payment terms. A financial plan models expected financial consequences. One is primarily contractual; the other is primarily analytical.
For example, a multi-year supplier agreement could influence the financial plan by establishing expected purchasing costs over several years. A lease could influence cash-flow assumptions and capital planning. A recurring service contract could create a predictable expense line. The financial model should therefore reflect the economic effect of agreements without pretending that the model itself creates contractual obligations.
Keeping these concepts separate improves clarity. The financial plan should record relevant assumptions from contracts and agreements, while the actual agreement should be reviewed according to its own legal and commercial requirements. If an agreement changes, the affected financial assumptions can then be updated without rebuilding the entire planning structure.
Common mistakes in long-term financial templates
One common mistake is excessive optimism. A model may assume strong revenue growth, stable costs, and consistently favorable investment results at the same time. This can make the final numbers look attractive but provide little decision value. A more credible model explains why each major assumption was selected and tests what happens when conditions are less favorable.
Another mistake is mixing actual results with forecasts without labeling the difference. Actual figures should be clearly distinguishable from planned or projected figures. Otherwise, later reviews become confusing because users cannot tell whether a number represents historical performance or an assumption about the future.
A third mistake is creating a model that is too complicated to maintain. A sophisticated structure is not automatically better. If users cannot understand the formulas or update the model consistently, errors become more likely. A practical template should contain enough detail to answer important questions while remaining understandable to the people responsible for maintaining it.
Reviewing and updating the plan
A long-term plan should be treated as a living management document. Review frequency depends on the situation. A business with rapidly changing revenue may review key assumptions monthly, while a household may conduct a detailed long-range review quarterly or annually. The important principle is to update the model when meaningful information changes rather than allowing the original assumptions to become permanently stale.
Each review should compare actual results with the assumptions that drove the original plan. Look for material differences in income, expenses, cash flow, debt, savings, investment values, or major project costs. Then decide whether the difference is temporary or represents a new trend. A one-time expense may not justify rewriting the long-range forecast, while a sustained change in income probably does.
It is also useful to preserve previous versions or clearly record revision dates. This creates a history of how expectations changed and why. Over time, that history can improve future planning because it shows which assumptions were consistently too optimistic, which costs were underestimated, and which targets were realistic.
Practical Solution
Start with a simple structure containing five layers: starting financial position, assumptions, annual forecast, goals, and scenario analysis. Do not begin by filling dozens of categories. First identify the handful of variables that actually drive the financial outcome. Once those are working correctly, add detail where it improves decision-making. This approach makes the model easier to audit and less likely to become a spreadsheet that looks sophisticated but is difficult to use.
For a personal plan, create one section for income, one for essential and discretionary expenses, one for savings and investments, one for debt, and one for major future goals. Add annual columns for the chosen horizon, then create monthly detail for the next year if needed. Connect savings and investment contributions to the cash-flow section so that the effect of each decision is visible rather than hidden.
For a business plan, build the revenue forecast from operational drivers where possible, then create the expense forecast, cash-flow statement, balance-sheet projection, capital expenditure schedule, debt schedule, and funding plan. Link these sections so that revenue, expenses, working capital, debt, and capital spending influence cash consistently. Add base, upside, and downside scenarios only after the base model has been checked.
Finally, establish a review routine. Record the plan date, major assumptions, target outcomes, and the next review date. During each review, compare actual performance with the original assumptions, identify material variances, and decide which assumptions should change. This turns a static worksheet into a practical management system for long-range decisions.
Using financial templates for better business decisions
A good financial model should ultimately support a decision. For example, a business may use it to determine whether expansion can be funded internally, whether additional borrowing may be required, or whether a planned investment should be delayed. The value comes from understanding the financial consequences of each option rather than simply producing a polished worksheet.
Financial planning can also improve communication. A business owner, finance manager, investor, lender, or board member may approach the same situation from a different perspective. A shared model provides a common set of assumptions and outputs that can be discussed. When assumptions are challenged, the model can be revised and the financial effect examined systematically.
Personal planning benefits from the same discipline. A long-term financial template can show whether a goal is being supported by sufficient savings, whether debt reduction is progressing, and whether major purchases fit within the broader financial position. It can also make competing priorities visible. Choosing to accelerate one goal may delay another, and the model helps quantify that trade-off.

Reference Examples
A financial long term Template is easiest to understand when readers can see how financial information is arranged across multiple periods. The examples below show different ways to organize income, expenses, cash flow, savings, investments, assets, liabilities, and net worth. Some examples emphasize annual planning, while others show detailed long-term worksheets or combined views. They should be treated as visual references rather than universal models, because the appropriate categories and assumptions depend on the individual or organization using the plan.
These visual references are useful for comparing layout choices before building or revising a long-range financial plan. Look at how each example separates summary information from detailed schedules, how years are arranged, how cash flow is distinguished from net worth, and how financial goals are connected to measurable figures. A strong template should make important relationships easy to inspect, provide enough detail for meaningful decisions, and remain understandable when reviewed months or years after it was first created.

RealMoneyPlan Personal Financial Plan – Long-Term Tab Pages 1-2
Source: RealMoneyPlan

RealMoneyPlan Personal Financial Plan – Long-Term Tab Pages 3-4
Source: RealMoneyPlan

RealMoneyPlan Personal Financial Plan – Long-Term Tab Pages 5-6
Source: RealMoneyPlan

RealMoneyPlan Family Financial Plan – Long-Term Tab Pages 1-2
Source: RealMoneyPlan

RealMoneyPlan Family Financial Plan – Long-Term Tab Pages 3-4
Source: RealMoneyPlan

RealMoneyPlan Family Financial Plan – Long-Term Tab Pages 5-6
Source: RealMoneyPlan

RealMoneyPlan Family Financial Plan – Long-Term Tab Pages 7-8
Source: RealMoneyPlan

RealMoneyPlan Personal Financial Plan – Annual Tab Pages 1-2
Source: RealMoneyPlan

RealMoneyPlan Personal Financial Plan – Annual Tab Pages 3-4
Source: RealMoneyPlan

RealMoneyPlan Personal Financial Plan – Annual Tab Pages 5-6
Source: RealMoneyPlan
